
Commercial Insurance · Windsor-Essex
Commercial Property Insurance
Commercial property insurance addresses direct physical loss or damage to the building, contents, stock, and equipment your business owns or is required to insure — subject to the causes of loss, limits, deductibles, and endorsements on your policy. Whether you own the premises, lease space, or rent out a commercial building, the insurable interests differ: landlords typically insure the shell; tenants often insure contents, inventory, and leasehold improvements; owner-occupiers may need both. Valuation basis (replacement cost versus actual cash value), coinsurance, vacancy conditions, and optional extensions for water damage, sewer backup, earthquake, or overland flood are policy-dependent — not automatic in every form. Business interruption is a separate coverage that may coordinate with property after a covered loss. Premium Insurance Brokers can help Windsor–Essex businesses compare property programs for how you actually occupy and use your premises.
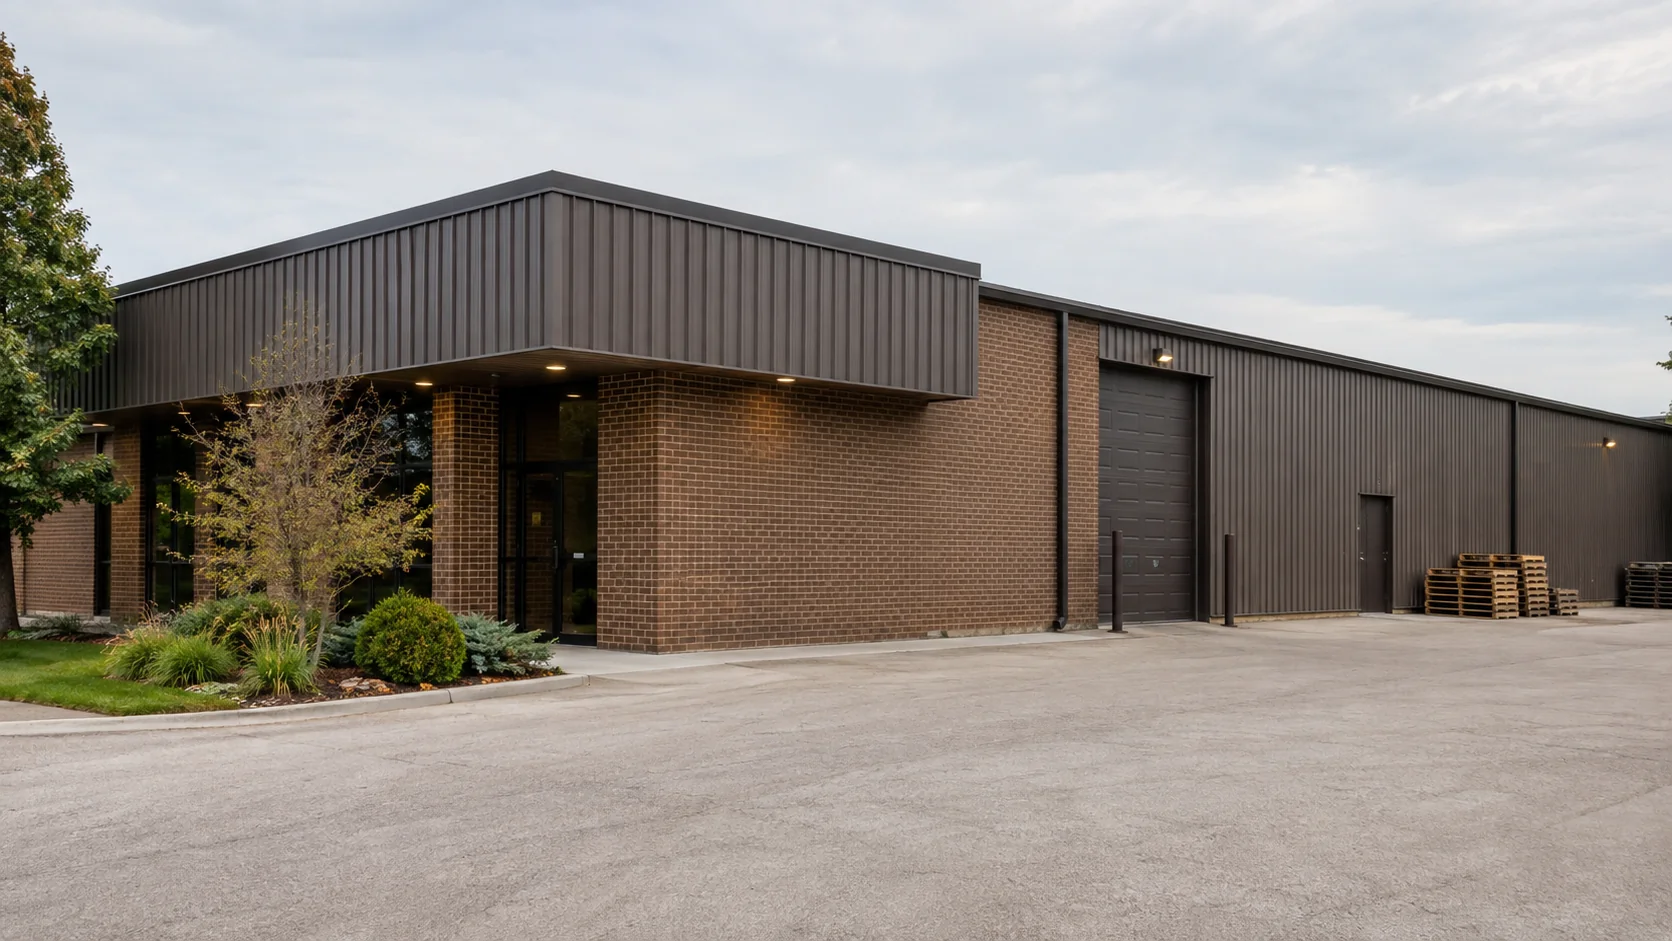
For Windsor–Essex businesses and commercial property owners insuring buildings, contents, inventory, and leasehold interests — reviewed through an independent broker who can coordinate property limits, optional endorsements, and business interruption where a covered loss would interrupt operations.
What's covered
Commercial property coverage is organized here by what you may need to insure — building, contents, optional equipment breakdown, and owner/lessor interests — because owned, leased, and rental-property exposures are structured differently on most policies.
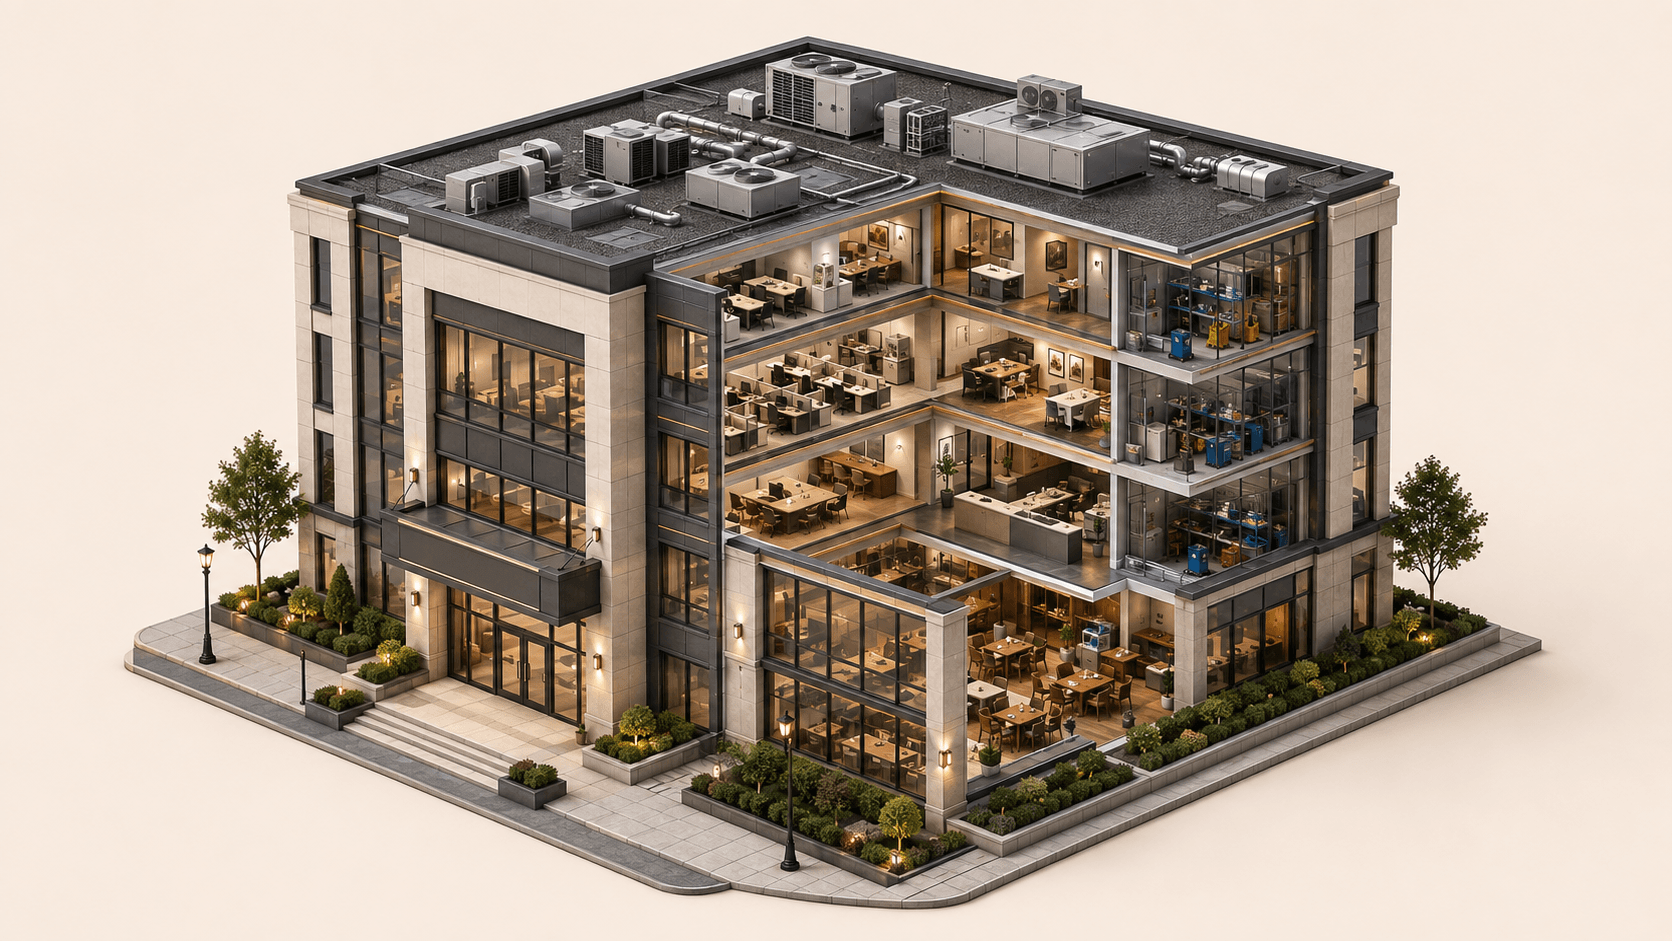
A fire doesn't pause your mortgage: When you own the building or are contractually required to insure it under a lease or mortgage, the structure and attached improvements often represent your largest fixed asset. A covered fire, windstorm, or other insured peril can damage walls, roof, and built-in systems long before operations resume. Building limits should reflect current replacement or repair values — and coinsurance or agreed-value provisions on many forms can reduce recovery if values are understated. Vacancy or unoccupancy conditions may also restrict coverage if the premises sit empty beyond policy thresholds.
A fire doesn't pause your mortgage
When you own the building or are contractually required to insure it under a lease or mortgage, the structure and attached improvements often represent your largest fixed asset. A covered fire, windstorm, or other insured peril can damage walls, roof, and built-in systems long before operations resume. Building limits should reflect current replacement or repair values — and coinsurance or agreed-value provisions on many forms can reduce recovery if values are understated. Vacancy or unoccupancy conditions may also restrict coverage if the premises sit empty beyond policy thresholds.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Commercial property FAQ
Straight answers to common questions for this industry.
Commercial property insurance may help respond to direct physical loss or damage to insured buildings, contents, equipment, and stock from covered perils — subject to causes of loss, limits, deductibles, and endorsements on your policy. It does not automatically cover every cause of loss, every piece of equipment, or income lost during repairs. Optional extensions for sewer backup, overland flood, earthquake, and equipment breakdown must be confirmed with your broker rather than assumed from a standard quote.
Ready when you are
Ready to protect your commercial property?
Share how you occupy the premises, what you own or lease, and current values — we will compare property options and optional endorsements that fit.