Personal Insurance · Windsor-Essex
Home insurance in Windsor-Essex
Looking for home or house insurance in Windsor, Essex County, or elsewhere in Ontario? We help homeowners compare dwelling, contents, liability, and additional living expenses through an independent brokerage.
Home insurance, sometimes called house insurance, is for owner-occupied homes in Windsor, Essex County, and elsewhere in Ontario. A typical policy is built from dwelling, contents, personal liability, and additional living expenses. Water endorsements are reviewed separately, because sewer backup and overland flood are often limited or excluded unless they are added. Homes with custom construction or high-value belongings may need limits beyond a standard default.
What's covered
Home insurance building blocks explained in plain language — what each part is meant to protect, and why it matters. Coverage, limits, and eligibility vary by insurer and policy.
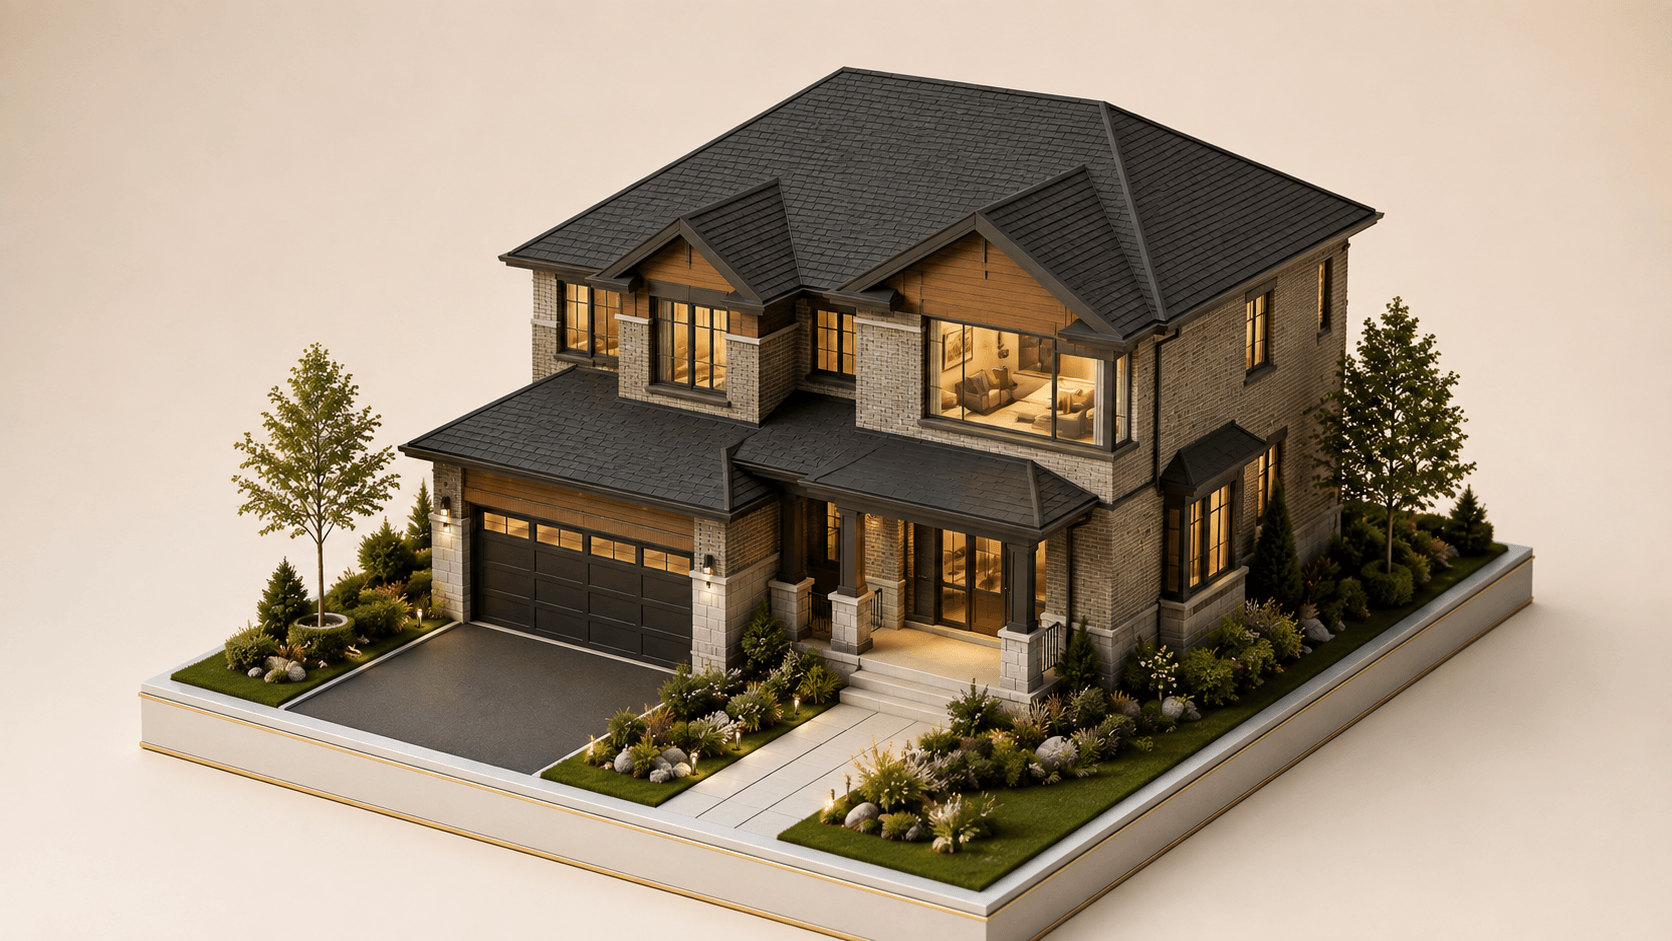
Dwelling: Dwelling coverage is intended to respond to damage to the house itself — walls, roof, and permanently attached components such as built-in cabinetry — subject to insured perils, deductibles, limits, and policy terms. Replacement cost vs. actual cash value, reconstruction costs in your area, and outbuildings may all affect how dwelling limits should be set.
Dwelling
Dwelling coverage is intended to respond to damage to the house itself — walls, roof, and permanently attached components such as built-in cabinetry — subject to insured perils, deductibles, limits, and policy terms. Replacement cost vs. actual cash value, reconstruction costs in your area, and outbuildings may all affect how dwelling limits should be set.
Practical considerations
High-value and custom homes
Unique architecture, imported materials, and specialty rooms (wine cellars, home theatres) may need itemized schedules and higher limits. Document upgrades so dwelling and contents values stay current.
Scheduled valuables
Jewellery, art, and collectibles often carry sub-limits under standard policies. Scheduling high-value items separately can provide clearer protection.
Liability limits
Properties with pools, trampolines, or frequent entertaining may warrant higher personal liability limits or an umbrella policy.
Water, sewer backup, and overland flood
These are different events. Sudden escape of water from plumbing, backup of sewers or drains, and overland water that enters from outside are often treated under different wording. Sewer backup and overland flood are frequently optional, sub-limited, or unavailable, depending on the insurer and the property. A finished basement, sump pump, or prior water loss should be disclosed. No home policy here promises flood or sewer-backup coverage.
What underwriters ask about the house
Insurers commonly ask the year built, roof age, heating, electrical and plumbing updates, claims history, occupancy, and whether the home is owner-occupied. Those facts decide which markets will quote and on what terms. Not every insurer offers the same endorsements, limits, or deductibles.
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your situation
Your property, belongings, or vehicle — and how you actually use them.
- 2
Multiple insurance markets
Independent access to personal lines carriers — not one company's shelf.
- 3
Premium broker
Windsor-Essex advice that explains options in plain language.
- 4
Right-fit coverage
Coverage matched to your real risks — not a one-size template.
A lot to protect? Good thing we have options.
Own a condominium, rent, or insure a rental property? Those policies are separate. If you are also insuring a car, auto insurance is quoted on its own.
Home insurance FAQ
Straight answers to common home insurance questions.
It isn't legally required in Ontario if you own your home free and clear, but it's strongly recommended. If you have a mortgage, your lender typically requires home insurance until the loan is paid off.
Ready when you are
Ready to protect your home?
Tell us about your property — we'll compare options and explain what actually fits.