Greenhouse & Nursery · Windsor-Essex
Greenhouse & Nursery Insurance
Greenhouse and nursery operations in Leamington, Essex County, and Windsor-Essex rely on specialized structures, climate systems, and growing stock that standard commercial packages may not describe the same way as a retail shop or office. Premium Insurance Brokers helps review property, equipment, liability, and related coverages for how your controlled-environment or nursery operation actually runs — without treating Health Canada–licensed cannabis cultivation as the same product route.
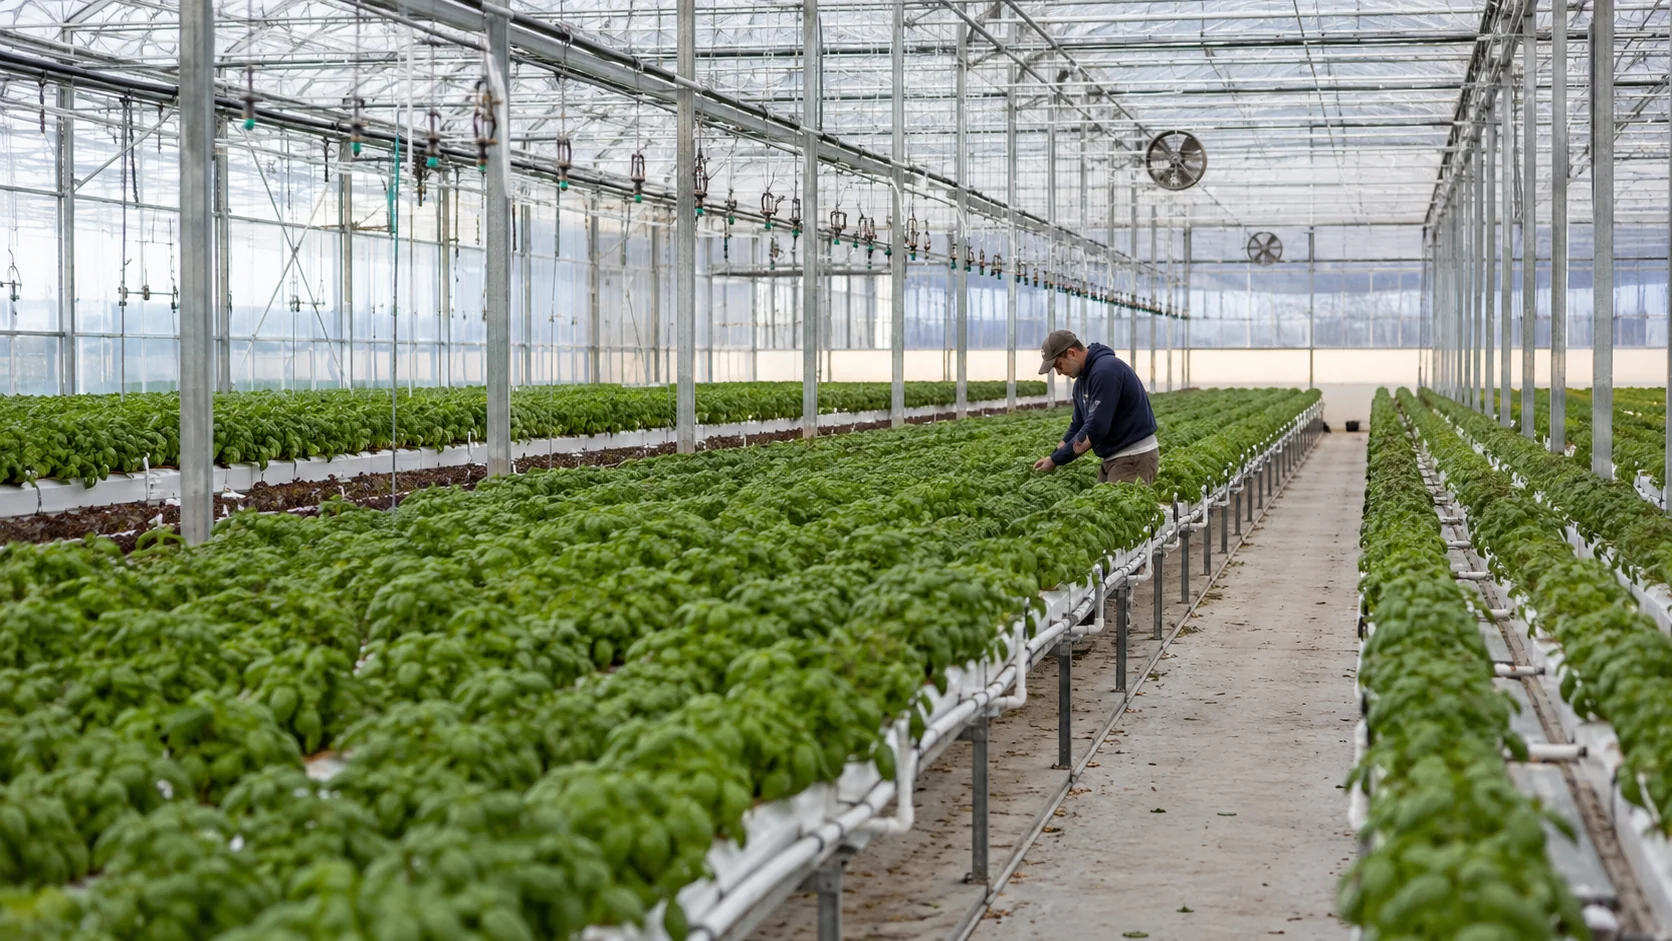
For greenhouse and nursery operators in Leamington, Essex County, and Windsor-Essex — reviewed through an independent broker who can coordinate structures, equipment, stock treatment, and liability without assuming every plant or crop exposure is automatic.
What's covered
Coverage areas commonly reviewed for greenhouse and nursery operations — what applies depends on your policy, insurer, scheduled property, and how growing stock is defined.
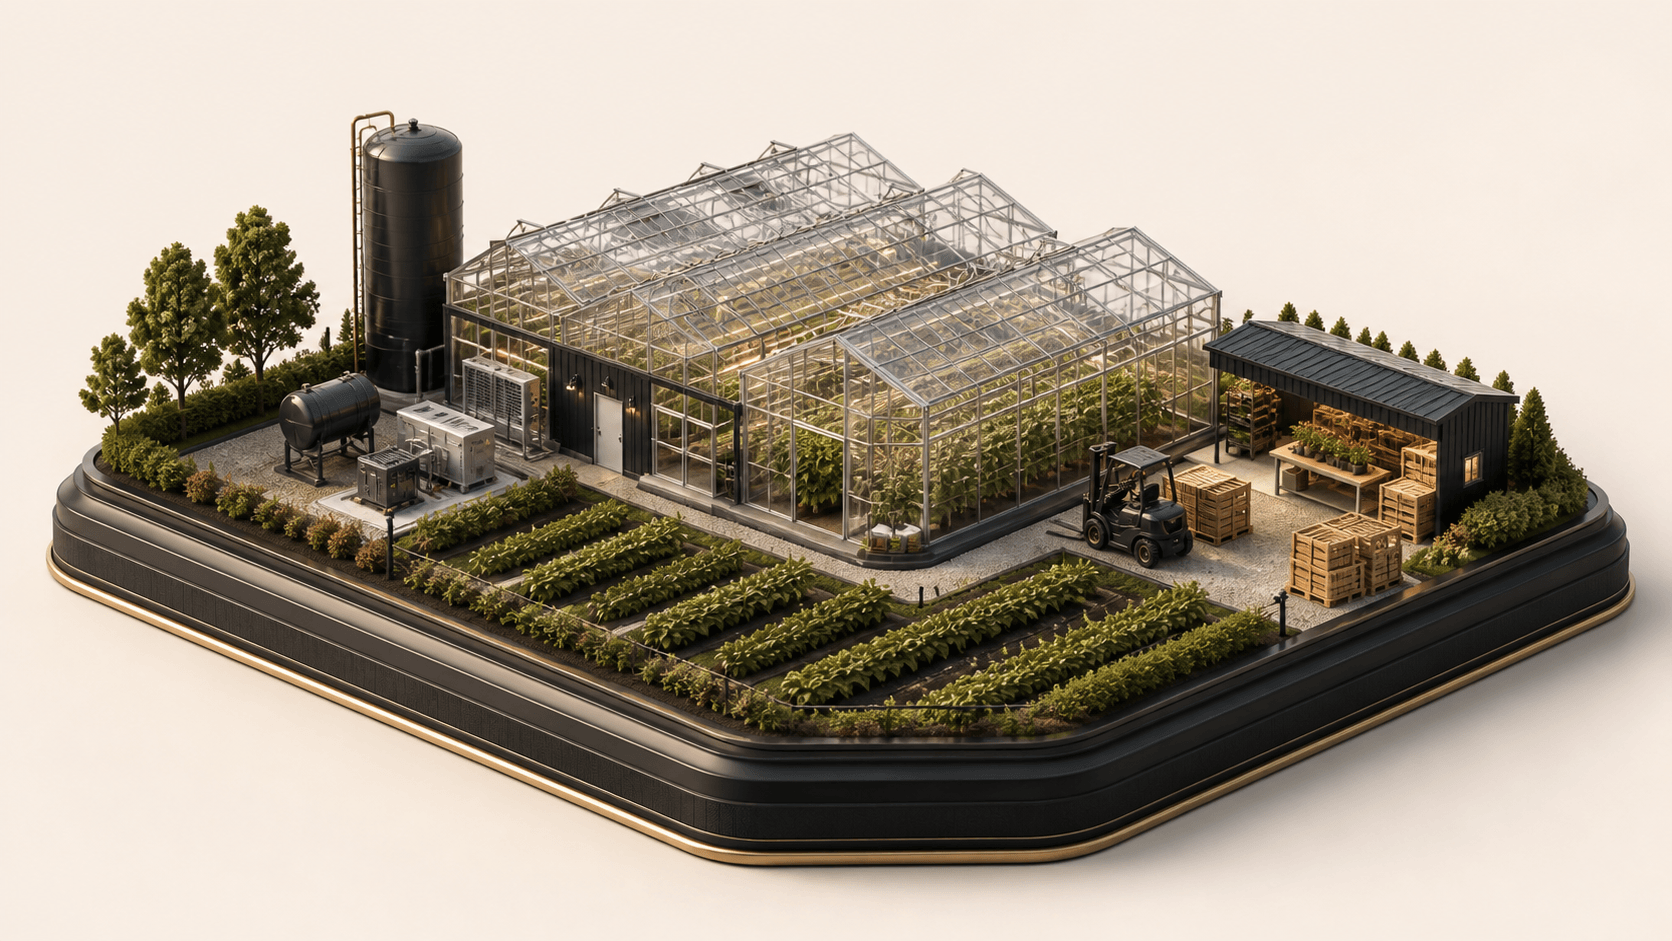
Why structures drive insurable values: Glass bays, poly tunnels, climate-controlled houses, and nursery buildings in Leamington and Essex County often represent a large share of total property values alongside tenant improvements and packing areas. Building types, construction, and total property values should be reviewed with your broker so limits and descriptions reflect the operation accurately.
Why structures drive insurable values
Glass bays, poly tunnels, climate-controlled houses, and nursery buildings in Leamington and Essex County often represent a large share of total property values alongside tenant improvements and packing areas. Building types, construction, and total property values should be reviewed with your broker so limits and descriptions reflect the operation accurately.
Practical considerations
Construction and total property values
Building types, construction, and total property values should be reviewed with your broker so limits and descriptions reflect the greenhouse or nursery accurately.
Heating, ventilation, and irrigation systems
Climate and irrigation systems are often central to these operations — your broker should review how they are described and insured.
Dependence on utilities and critical equipment
Operations that depend heavily on utilities and critical equipment may need careful review of how downtime and equipment failure are treated under the policy.
Business interruption exposure
The financial impact of a shutdown can vary by season and operation — business interruption limits and terms warrant a focused broker review.
Treatment of plants, nursery stock, and growing inventory
How plants, nursery stock, and growing inventory are treated can vary significantly by policy and insurer — this should be reviewed rather than assumed.
Seasonal changes in values or operations
Seasonal shifts in inventory, revenue, or operations may affect what should be reported and when limits need updating.
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
Open-field farms, crop programs, livestock, and equipment scheduling are separate Agriculture routes — cannabis cultivation stays on its own commercial product page.
Greenhouse & nursery FAQ
Straight answers to common questions.
It depends on the operation. Structures, specialized equipment, business property, growing stock treatment, liability, business interruption, and equipment breakdown are commonly reviewed. Premium can help identify coverages that should be considered for how you operate — without promising that any specific item or peril is automatic.
Ready when you are
Ready to discuss your greenhouse or nursery?
Tell us about your structures, systems, and stock — a broker will compare options and explain what may fit.