
Commercial Insurance · Windsor-Essex
Contractors Insurance
Contractors insurance is about the operating contracting business — the trade or general contractor that bids work, manages crews and subcontractors, and moves between job sites. Commercial general liability addresses certain third-party injury and property-damage claims arising from your operations. Tools and contractors equipment coverage, where purchased, addresses owned tools and mobile equipment. Project property (builder's risk) and wrap-up or OCIP programs are usually project-specific overlays — not substitutes for ongoing business coverage. Needs differ across general contractors, electricians, plumbers and HVAC, roofers, excavation and concrete trades, renovators, and landscapers. Premium Insurance Brokers can help Windsor-Essex contractors align certificates, additional-insured requests, and trade exposures with how you actually work.
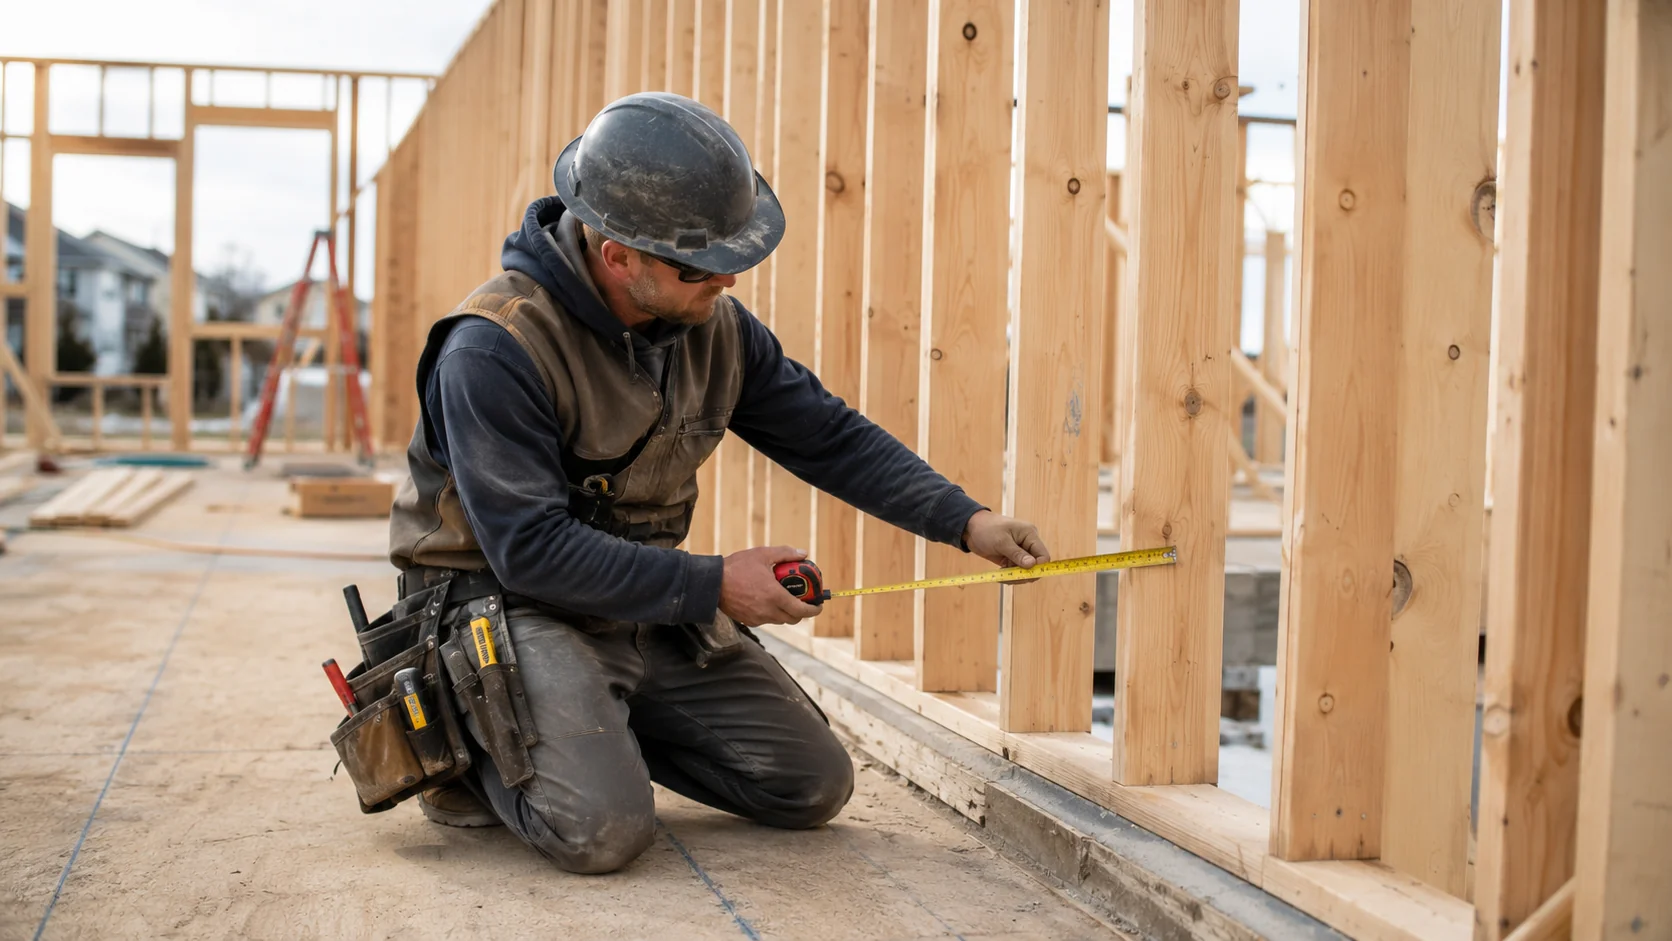
For Windsor–Essex general contractors and trade contractors — reviewed through an independent broker who can align liability, tools, certificates, and project participation with how you actually build.
What's covered
Core coverages for the operating contractor — liability and tools for ongoing work, plus project property and wrap-up participation when a specific job requires them.
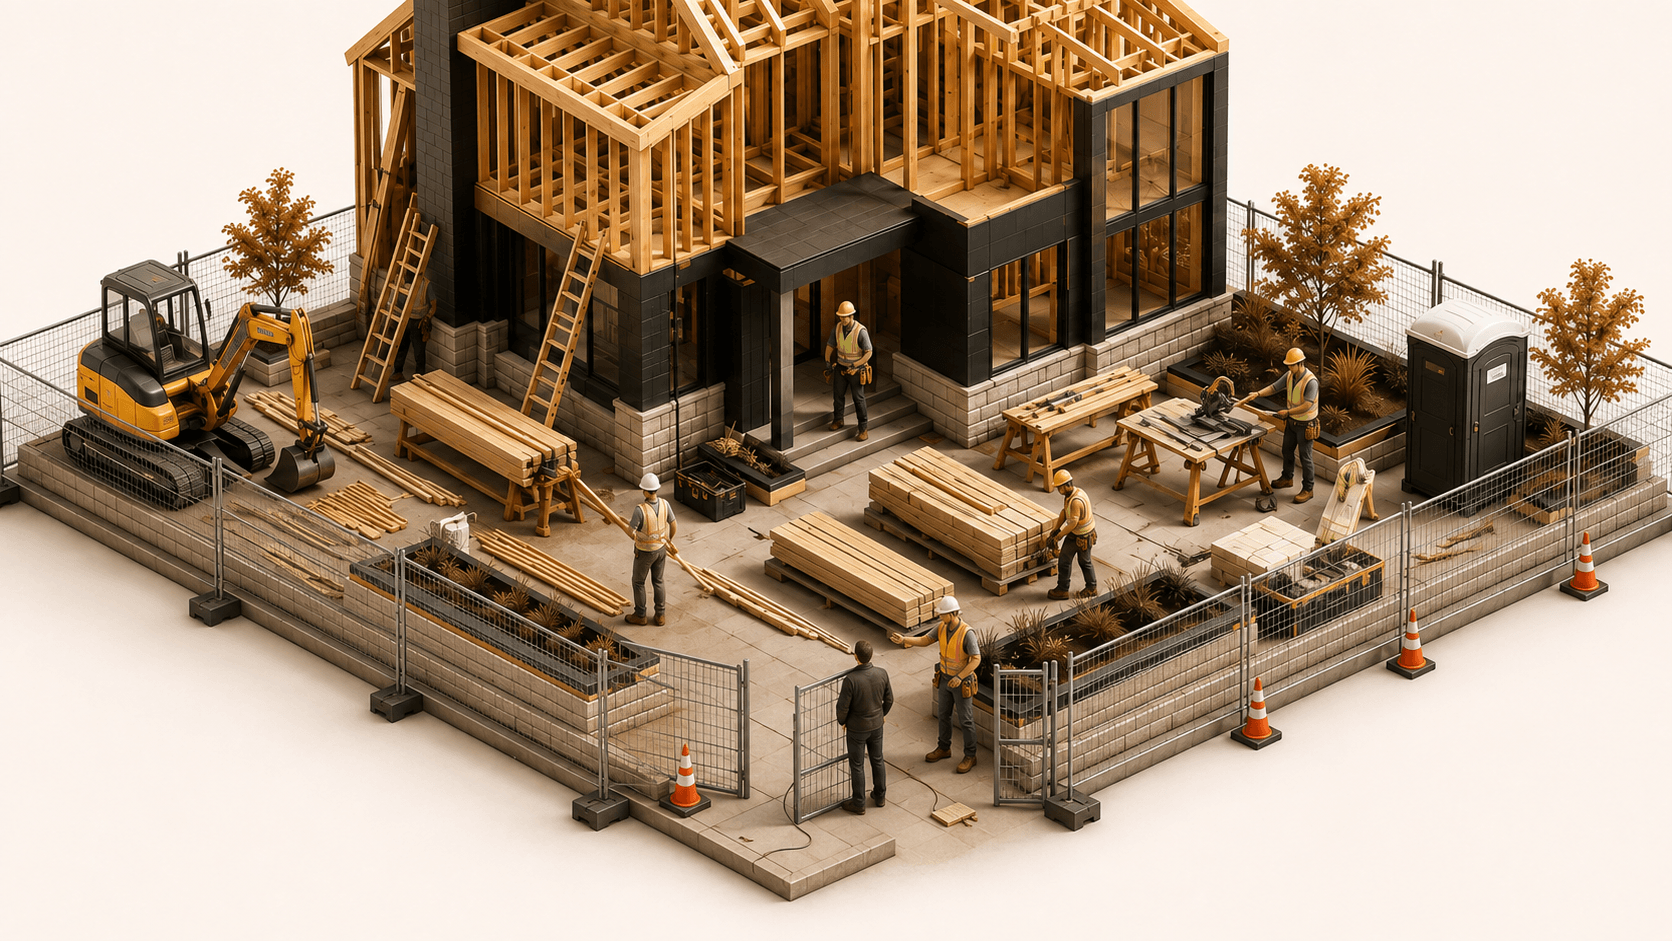
Job-site injury claims follow your operations — not the owner's property policy: CGL addresses third-party claims from your work — slips, property damage, and certain completed-operations allegations depending on wording. It does not insure your tools, your vehicles, or the building under construction. Contractual additional-insured and waiver requests must match actual policy capabilities.
Job-site injury claims follow your operations — not the owner's property policy
CGL addresses third-party claims from your work — slips, property damage, and certain completed-operations allegations depending on wording. It does not insure your tools, your vehicles, or the building under construction. Contractual additional-insured and waiver requests must match actual policy capabilities.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Contractors insurance FAQ
Straight answers to common questions for this industry.
Generally no. CGL addresses certain third-party bodily injury and property-damage claims arising from your operations — subject to policy terms. Stolen or damaged tools need tools/equipment or inland marine coverage where purchased. Company vehicles need commercial automobile coverage. Do not rely on CGL alone for tools or highway auto exposures.
Ready when you are
Ready to cover your contracting business?
Share your trade, revenue, equipment, and contract requirements — we will compare liability, tools, and project participation options.