
Commercial Insurance · Windsor-Essex
Small Business Insurance
There is no single universal small-business insurance policy. Windsor–Essex owner-operators, storefronts, home-based businesses, and growing teams typically assemble coverage through a business owners policy, commercial package policy, or separate policies and endorsements — depending on industry, revenue, premises, vehicles, and contract requirements. General liability may address certain third-party injury and property-damage claims; commercial property may cover contents, inventory, and tenant improvements; commercial auto applies when you own, lease, or regularly use vehicles for operations; business interruption — where purchased with property — may help with income after a covered physical loss. Cyber, crime, professional liability, and product liability are often added when operations warrant them — not every small business needs every coverage on day one. Premium Insurance Brokers can help map a practical program to how you actually operate rather than selling a one-size-fits-all bundle.
For Windsor–Essex owner-operators, storefronts, home-based businesses, and growing teams assembling their first commercial program — reviewed through an independent broker who can compare package policies, endorsements, and separate coverages for how you actually operate.
What's covered
Small business insurance is organized here by four broad coverage categories most Windsor–Essex businesses review first — because liability, property, vehicles, and income interruption are common starting points before industry-specific endorsements are added.
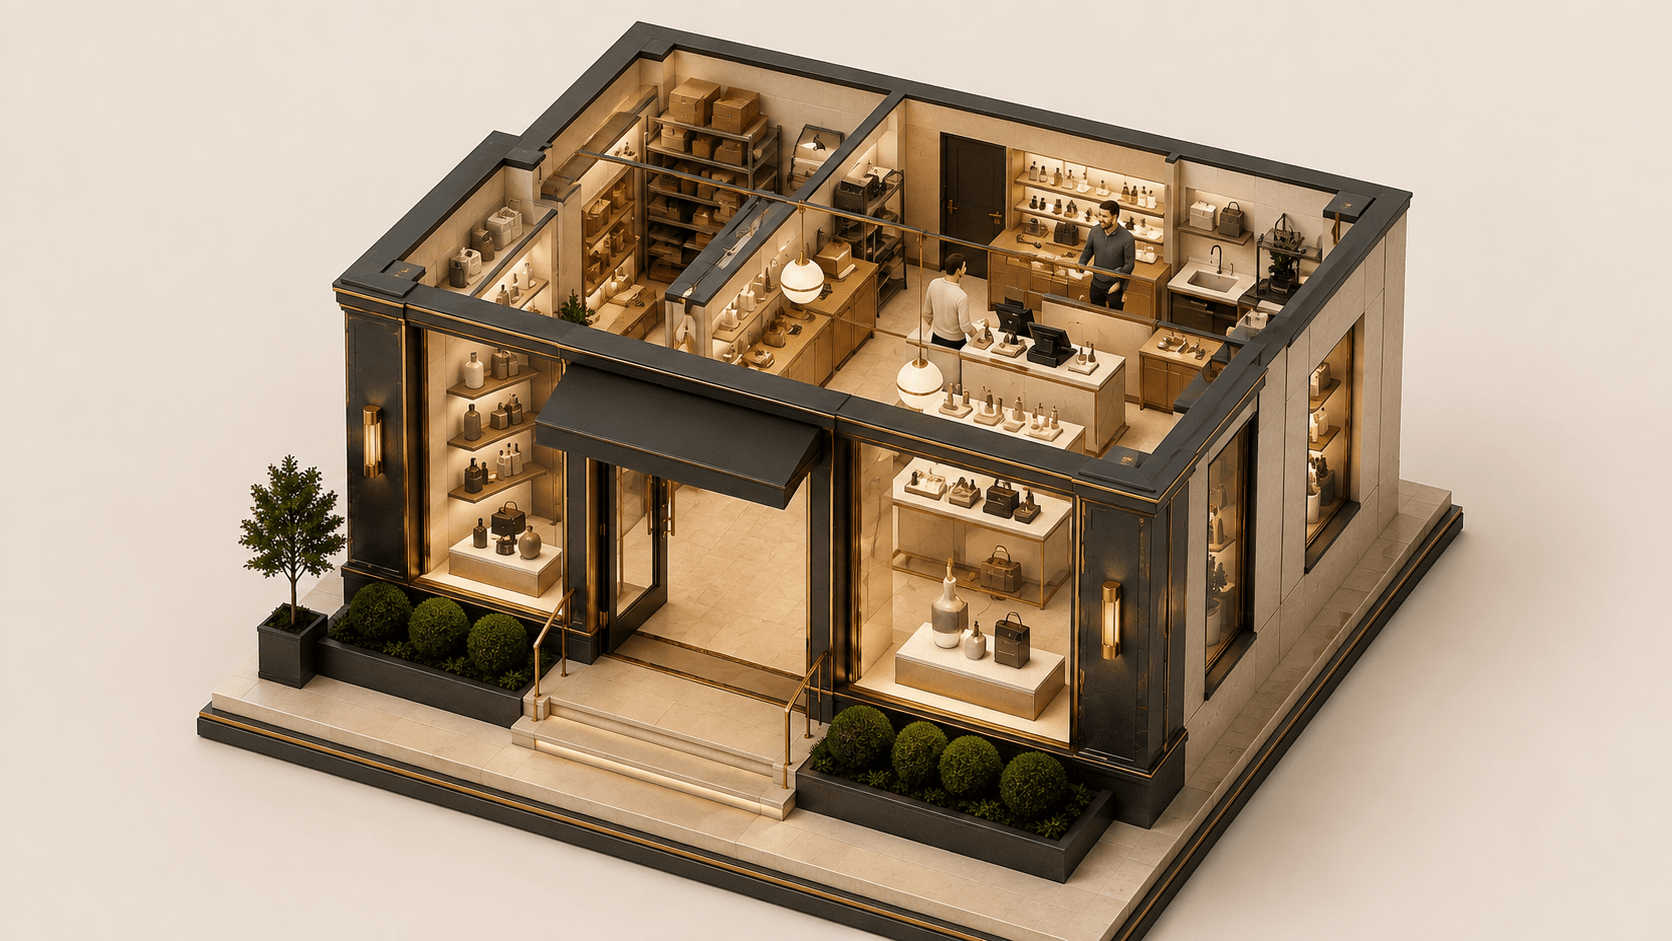
A customer slip-and-fall is often a GL claim: Retail shops, offices, and service businesses with public contact face premises and operations liability — a visitor injury, damage to a client's property on site, or certain product-related claims may fall under commercial general liability when covered by the form. GL does not replace professional liability for advice errors, cyber coverage for data breaches, or property insurance for your own equipment. Contractual certificate requirements from landlords and clients often start with GL limits and additional insured status.
A customer slip-and-fall is often a GL claim
Retail shops, offices, and service businesses with public contact face premises and operations liability — a visitor injury, damage to a client's property on site, or certain product-related claims may fall under commercial general liability when covered by the form. GL does not replace professional liability for advice errors, cyber coverage for data breaches, or property insurance for your own equipment. Contractual certificate requirements from landlords and clients often start with GL limits and additional insured status.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Small business insurance FAQ
Straight answers to common questions.
Most Windsor–Essex small businesses start by reviewing general liability and commercial property if they have equipment, inventory, or public premises contact. Businesses that own or regularly use vehicles need commercial auto or hired/non-owned auto coverage. Business interruption may matter when a covered property loss would interrupt income. Professional advice, cyber exposure, crime, and product liability are added when operations warrant them — there is no single mandatory bundle for every business type.
Ready when you are
Ready to protect your small business?
Tell us what you do, where you operate, and what you own — we will compare package and separate-policy options that fit your stage of growth.