
Commercial Insurance · Windsor-Essex
Condominium Corporation Insurance
This page is for Ontario condominium corporations — the corporation's master insurance program — not for individual unit owners (see Condo Insurance for unit-owner coverage). Under the Condominium Act, 1998, corporations must obtain and maintain property insurance for damage to units and common elements caused by major perils and other perils specified in the declaration or by-laws, to replacement cost subject to a reasonable deductible — excluding improvements to units above the standard unit definition. Corporations must also maintain liability insurance for common-element occupier exposure and certain machinery and motor vehicle liabilities under s.102, and must purchase and maintain directors' and officers' insurance for board members if reasonably available under s.39. Master policy deductibles are treated as common expenses, and chargeback rules may apply to owners under s.105 — subject to corporation by-laws. Equipment breakdown is not statutory; it may be added where appropriate. Premium Insurance Brokers can help Windsor–Essex boards and property managers review corporation programs alongside unit-owner coordination.
For Ontario condominium corporations, boards, and property managers arranging master policies in Windsor–Essex — reviewed through an independent broker who can coordinate statutory property and liability requirements, optional equipment breakdown, and s.39 directors and officers insurance alongside unit-owner policy coordination.
What's covered
Condominium corporation insurance is organized here by the four program pillars boards most often review — master property, common-element liability, optional equipment breakdown, and directors and officers insurance — because corporation and unit-owner responsibilities are legally distinct under Ontario's Condominium Act.
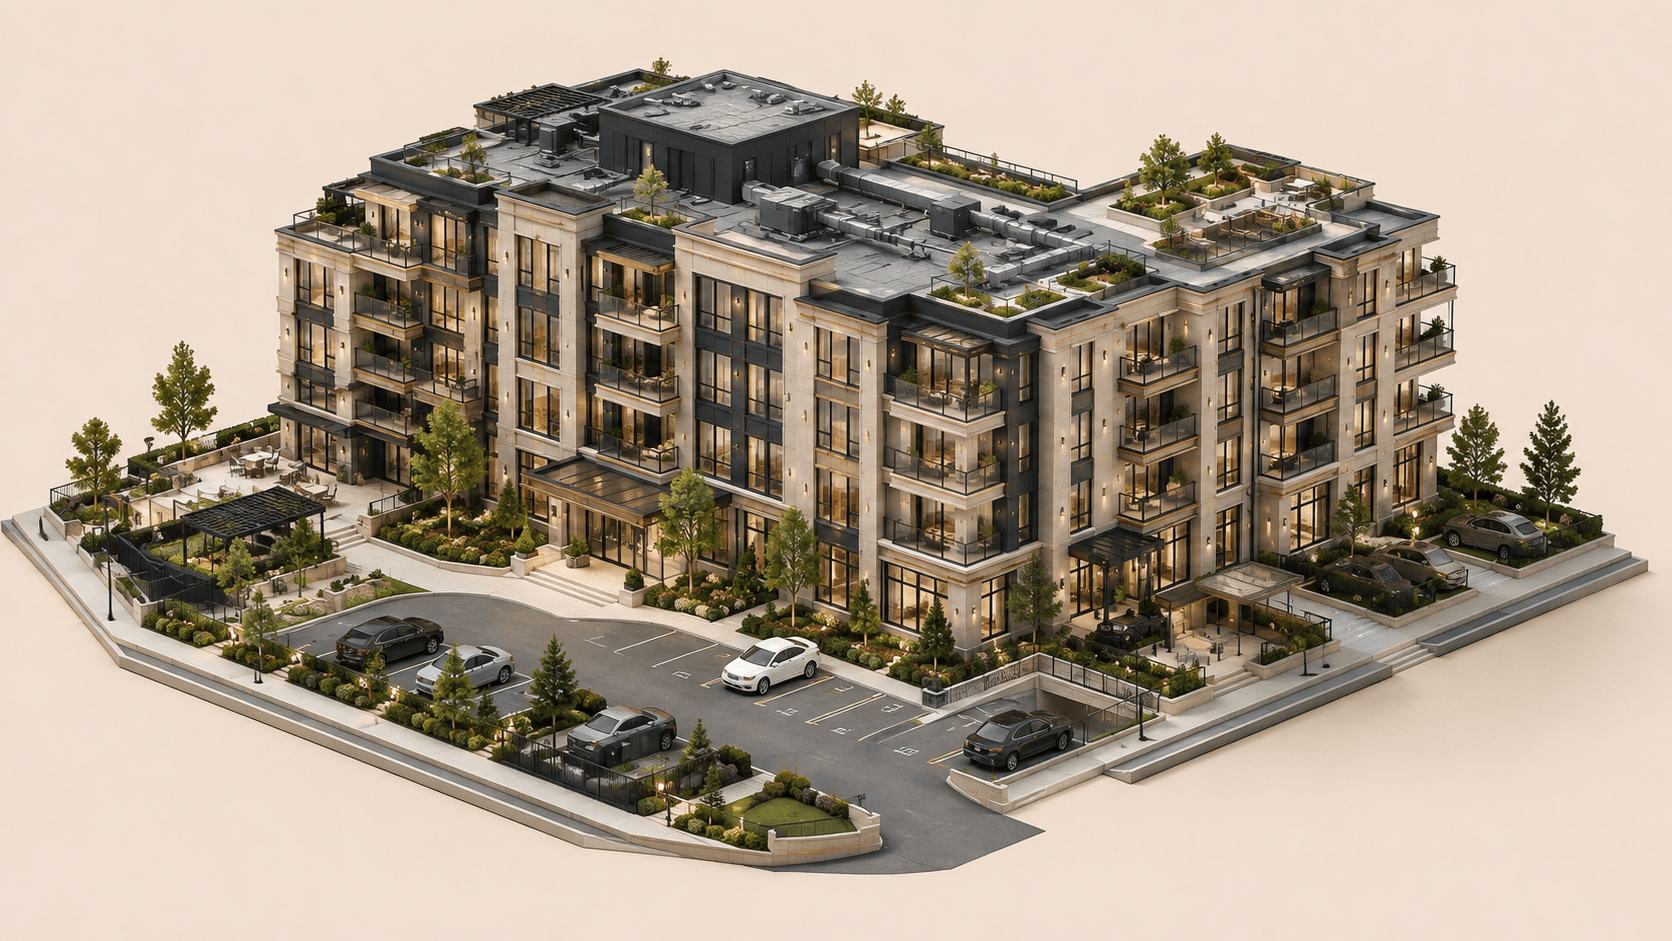
A pipe burst can reach units and corridors at once: The master policy insures units to the standard unit definition and common elements against major perils under s.99 of the Condominium Act — not overland flood, which is not listed as a major peril in the Act and is typically a separate commercial property endorsement where available. Owner-installed improvements and betterments above the standard unit are excluded from the corporation's property insurance obligation under s.99(4). What counts as a standard unit is set by a corporation by-law under s.56(1)(h) or the declarant's schedule under s.43(5)(h) if no by-law exists — review your corporation's documents rather than assuming a universal definition.
A pipe burst can reach units and corridors at once
The master policy insures units to the standard unit definition and common elements against major perils under s.99 of the Condominium Act — not overland flood, which is not listed as a major peril in the Act and is typically a separate commercial property endorsement where available. Owner-installed improvements and betterments above the standard unit are excluded from the corporation's property insurance obligation under s.99(4). What counts as a standard unit is set by a corporation by-law under s.56(1)(h) or the declarant's schedule under s.43(5)(h) if no by-law exists — review your corporation's documents rather than assuming a universal definition.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Condominium corporation FAQ
Straight answers to common questions.
Under s.99 of the Condominium Act, 1998, the corporation must obtain and maintain property insurance for damage to units and common elements caused by major perils — fire, lightning, smoke, windstorm, hail, explosion, water escape, and other perils listed in the Act — plus additional perils specified in the declaration or by-laws, to replacement cost subject to a reasonable deductible. The corporation's obligation does not include insurance for improvements to units above the standard unit definition under s.99(4). Overland flood is not a listed major peril in the Act.
Ready when you are
Insuring a condominium corporation?
Share building type, amenities, standard-unit by-law status, and current master policy details — we will review corporation coverage against Condominium Act requirements.