
Commercial Insurance · Windsor-Essex
Hotel & Motel Insurance
Hotels and motels combine guest rooms, common areas, and amenities into overlapping property, liability, and income exposures. Depending on your operation, that can mean commercial property for the building and furnishings, general liability for guest injuries in lobbies, pools, or parking areas, business interruption when a covered loss closes rooms, and — where you operate a licensed bar or restaurant — liquor liability separate from standard commercial general liability. Ontario's Innkeepers Act can limit an innkeeper's statutory liability for guest goods in specified circumstances — separate from what your commercial property policy covers for your own assets. Premium Insurance Brokers can help align coverage to your room count, amenities, and seasonality.
For Windsor–Essex independent hotels, motels, inns, and extended-stay operators — reviewed through an independent broker who can coordinate property, liability, business interruption, and licensed alcohol coverage for how you actually operate.
What's covered
Hotel and motel insurance usually combines property protection for the building and furnishings, liability for guest and visitor incidents, and income coverage when a covered loss interrupts operations — with additional review where pools, licensed restaurants or bars, or event spaces are part of the property.
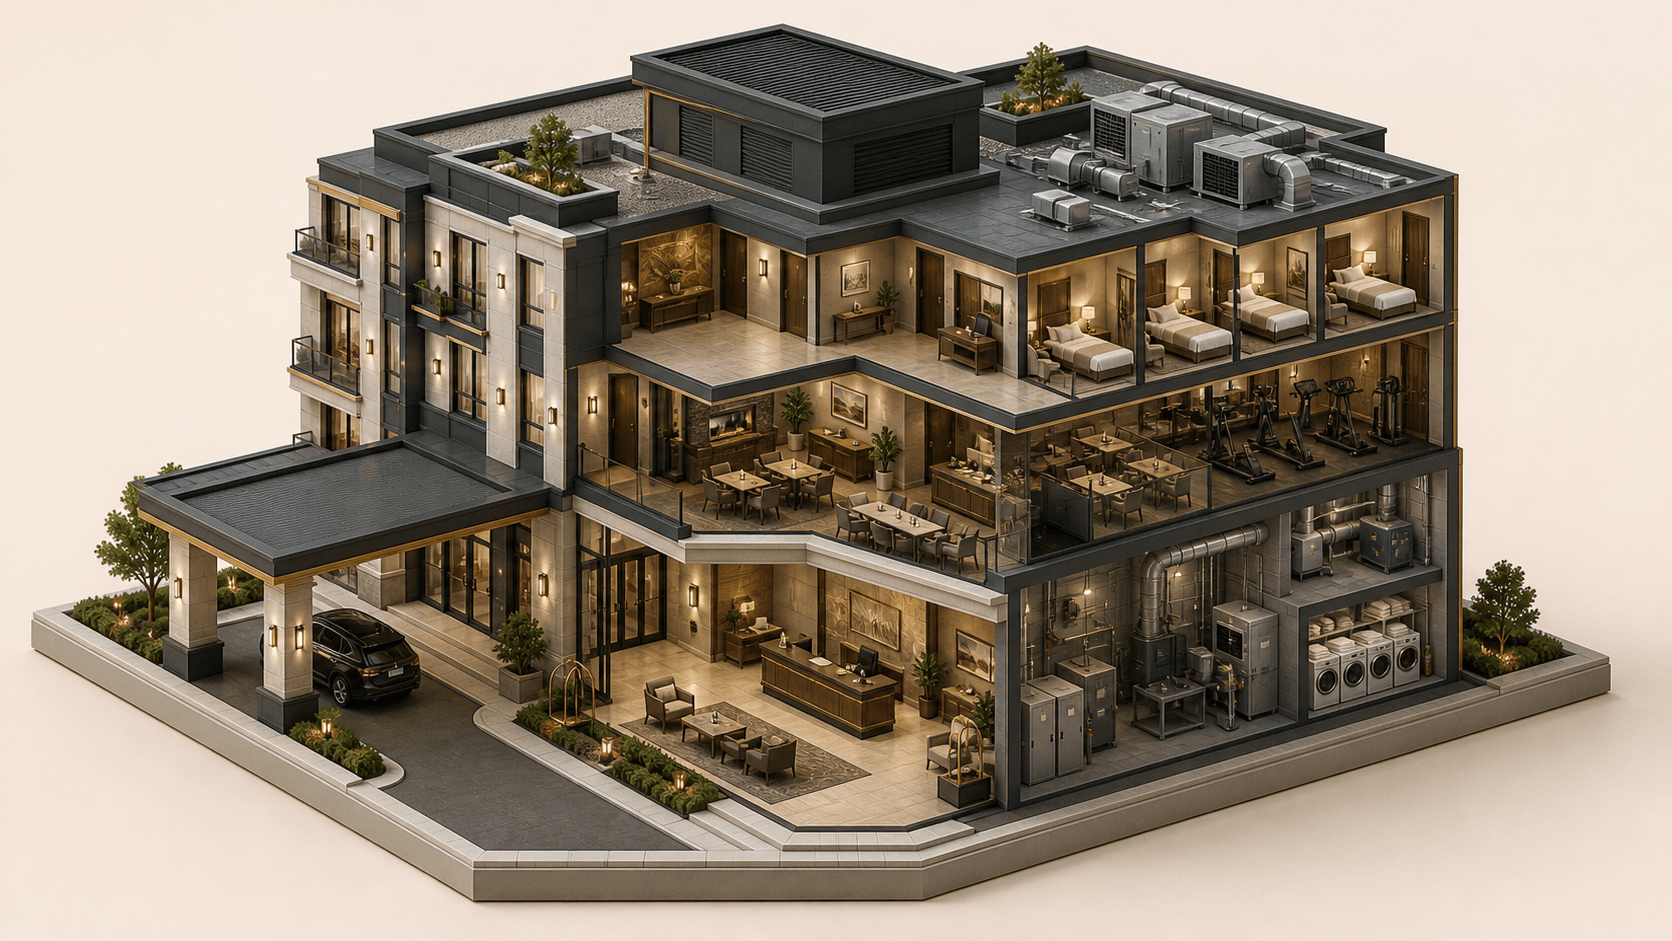
Guest rooms and back-of-house equipment drive property values: Hotels concentrate insurable value in guest rooms, lobbies, commercial laundry, HVAC, kitchen equipment, and furnishings — often across multiple floors and outbuildings. Fire, water escape from suppression systems, theft of linens or equipment, and seasonal occupancy swings affect how carriers structure property limits and deductibles. Guest personal belongings are typically excluded from the operator's property policy; under the Innkeepers Act, statutory liability for guest goods may be limited in specified circumstances, with exceptions for loss through the innkeeper's wilful act, default, or neglect and for goods expressly deposited for safekeeping — separate from insuring your own property.
Guest rooms and back-of-house equipment drive property values
Hotels concentrate insurable value in guest rooms, lobbies, commercial laundry, HVAC, kitchen equipment, and furnishings — often across multiple floors and outbuildings. Fire, water escape from suppression systems, theft of linens or equipment, and seasonal occupancy swings affect how carriers structure property limits and deductibles. Guest personal belongings are typically excluded from the operator's property policy; under the Innkeepers Act, statutory liability for guest goods may be limited in specified circumstances, with exceptions for loss through the innkeeper's wilful act, default, or neglect and for goods expressly deposited for safekeeping — separate from insuring your own property.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Hotel & motel FAQ
Straight answers to common questions.
Guest personal property is typically excluded from the operator's property policy. Guests generally rely on their own travel or homeowners insurance for belongings. Under Ontario's Innkeepers Act, an innkeeper's liability for guest goods may be limited in specified circumstances, with exceptions for loss through the innkeeper's wilful act, default, or neglect and for goods expressly deposited for safekeeping. Conspicuous posting of section 4 is relevant to obtaining the Act's benefit — a legal liability framework separate from insuring your own building, furnishings, and equipment.
Ready when you are
Operate a hotel or motel?
Share room count, amenities, and food service — we will compare hospitality programs.