
Personal Insurance · Windsor-Essex
Mobile & Manufactured Home Insurance
Coverage tailored to manufactured and mobile homes — from the structure and skirting to liability and personal belongings.
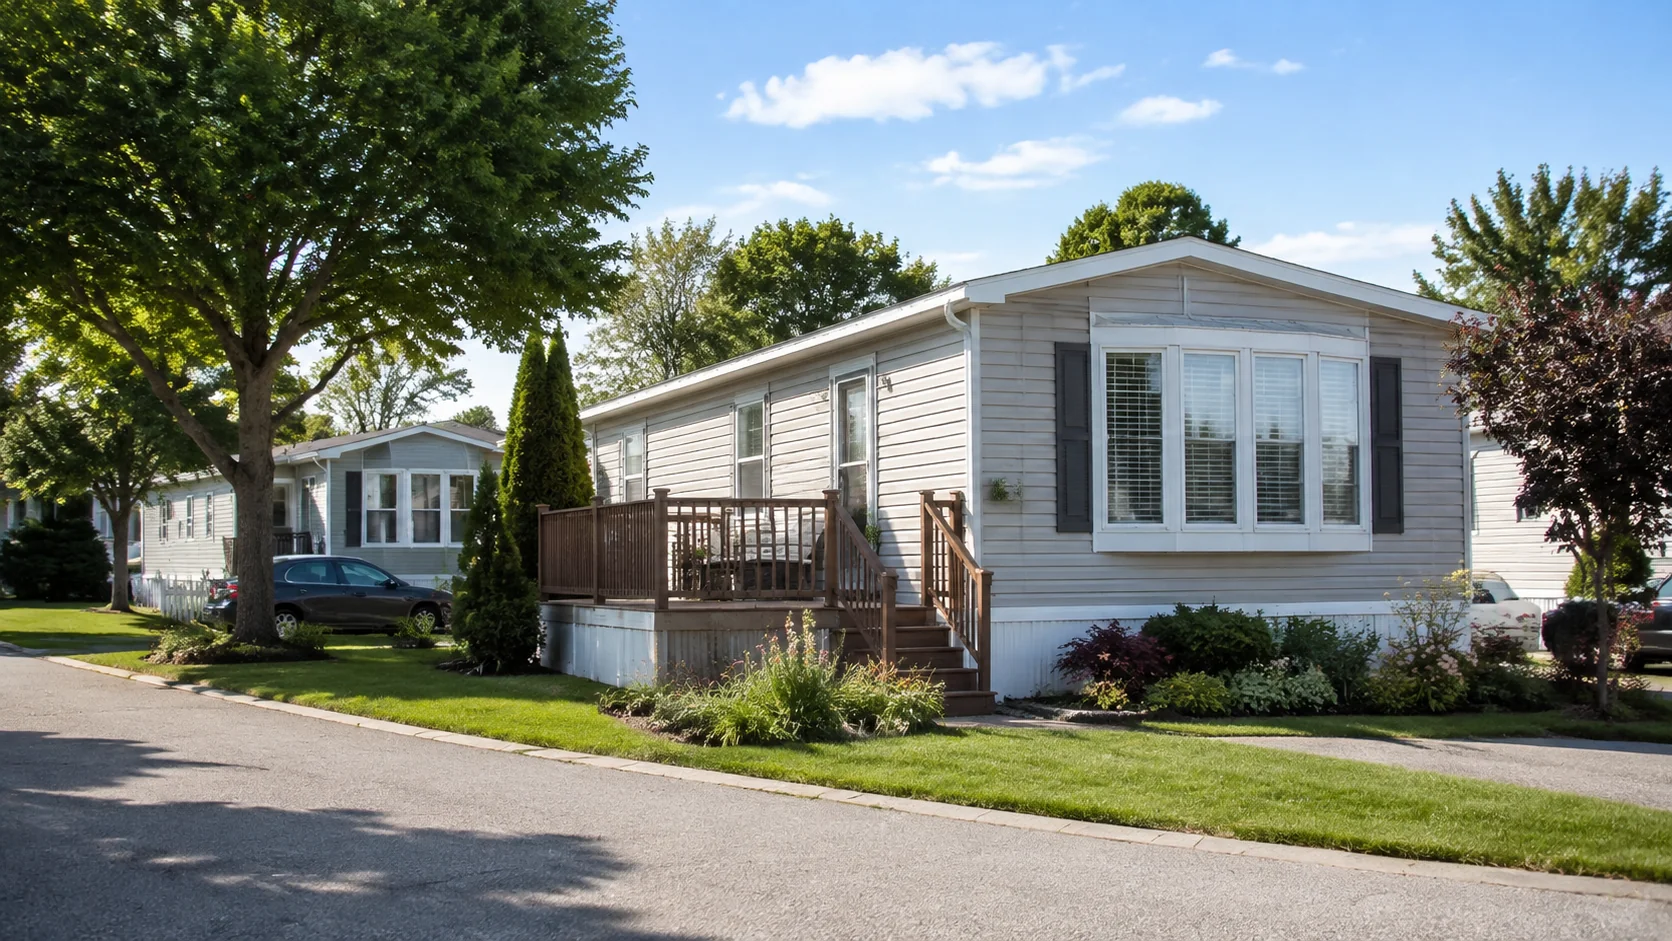
Mobile home insurance is for Windsor-Essex owners of manufactured and mobile homes — whether the unit sits on owned land, a leased lot, or a park. Coverage needs differ from conventional home policies based on construction type, tie-downs, and how the home is titled.
What's covered
Manufactured and mobile home policies address structure, belongings, outbuildings, and liability in ways that differ from ordinary site-built homeowners forms. Coverage, limits, and eligibility vary by insurer and policy. Your broker can help determine the options available for your situation.
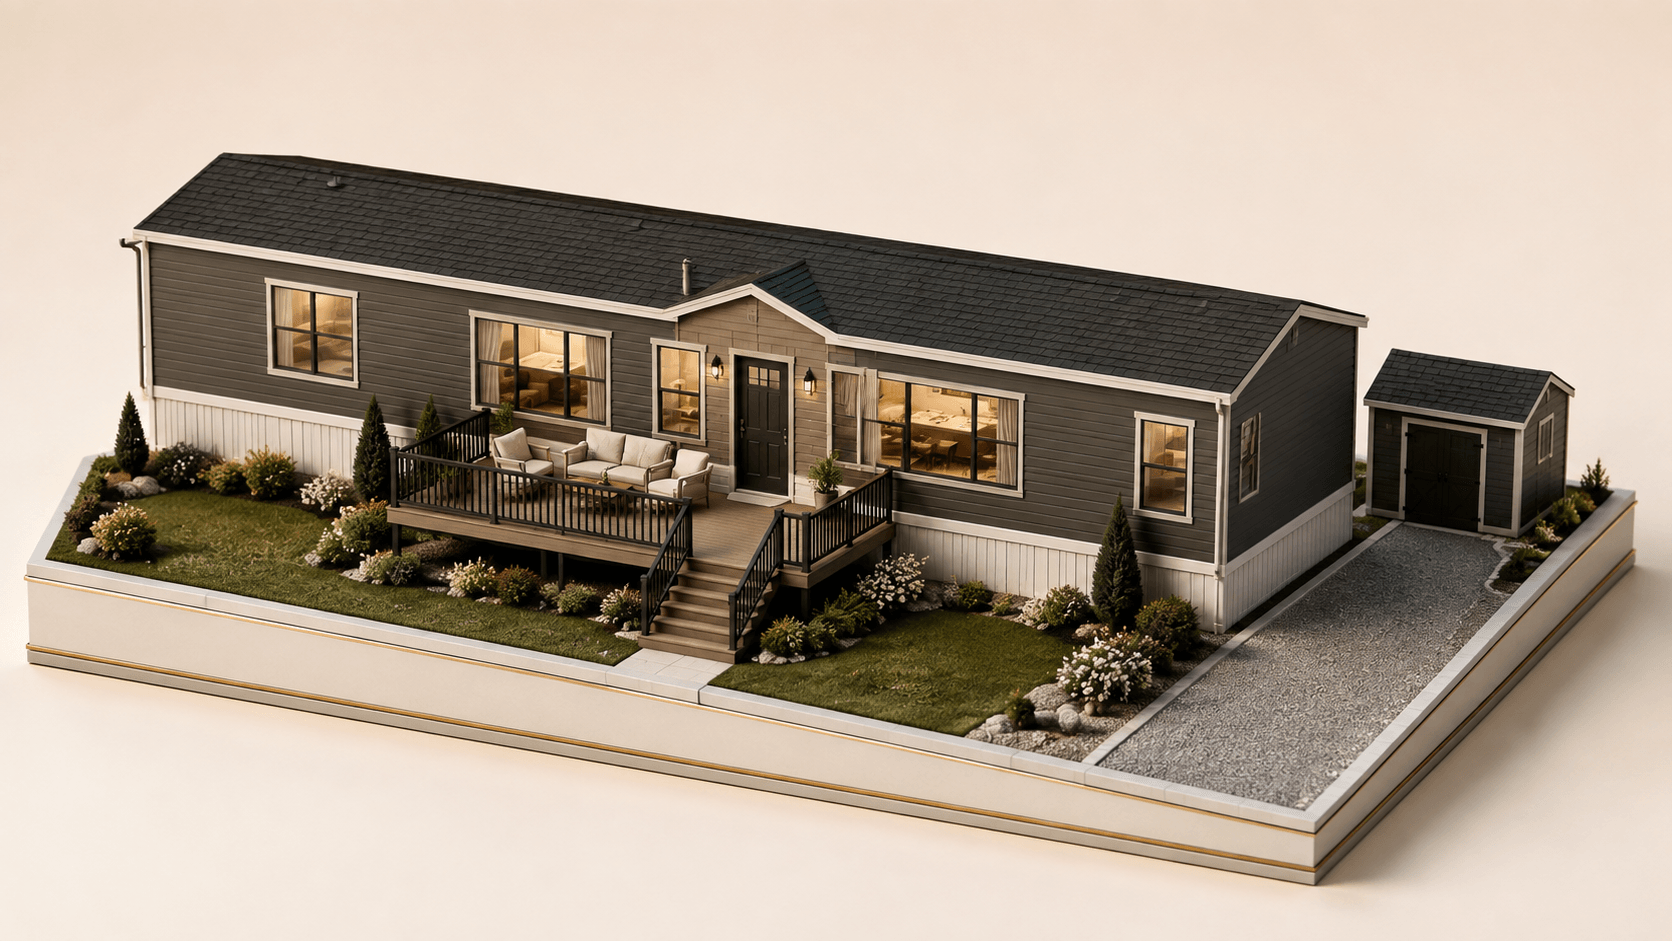
Manufactured / Mobile Dwelling: Dwelling coverage for a manufactured or mobile home is intended to respond to covered damage to the unit itself — subject to the home's age, condition, installation, and policy terms. These homes are built and often titled differently from site-built houses, so a conventional homeowner form may not apply without qualification.
Manufactured / Mobile Dwelling
Dwelling coverage for a manufactured or mobile home is intended to respond to covered damage to the unit itself — subject to the home's age, condition, installation, and policy terms. These homes are built and often titled differently from site-built houses, so a conventional homeowner form may not apply without qualification.
Practical considerations
Age and condition
Older units may have different insurability and valuation approaches. Document renovations, roof updates, and electrical upgrades when discussing options.
Land owned vs. leased lot
Whether you own the land or rent a pad in a mobile home park affects liability exposures and what structures need to be listed on the policy.
Tie-downs and wind exposure
Proper anchoring and skirting can matter for wind-related claims. Carriers may ask about installation standards and maintenance.
Seasonal or full-time occupancy
Vacancy periods, snowbird use, or renting the unit to others can change eligibility and required endorsements — disclose how the home is used.
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your situation
Your property, belongings, or vehicle — and how you actually use them.
- 2
Multiple insurance markets
Independent access to personal lines carriers — not one company's shelf.
- 3
Premium broker
Windsor-Essex advice that explains options in plain language.
- 4
Right-fit coverage
Coverage matched to your real risks — not a one-size template.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other personal coverage from Premium.
Mobile home insurance FAQ
Questions owners ask about manufactured home coverage.
Not exactly. Manufactured homes are built to different standards and often titled differently than site-built houses. Policies are designed around those construction and occupancy differences — a standard homeowner form may not apply.
Ready when you are
Own a manufactured or mobile home?
Share your unit details, lot arrangement, and occupancy — we will compare options that reflect how your home is actually used.