
Commercial Insurance · Windsor-Essex
Professional Offices Insurance
Professional offices combine premises where clients visit, equipment and records that keep the practice running, and — for many firms — advice or design services that create a separate professional liability exposure. Depending on your operation, that can mean commercial general liability for visitor injury, commercial property for contents and leasehold improvements, professional liability or E&O where you deliver professional services to clients, and cyber or privacy coverage where you store sensitive data — each subject to the policies you purchase. This page focuses on coordinating the office's commercial program; deep E&O mechanics for standalone professional liability are covered on our Professional Liability page.
For Windsor–Essex professional service firms operating from commercial offices — reviewed through an independent broker who can coordinate general liability, property, professional liability, and cyber coverage for how your office actually runs.
What's covered
Office insurance usually separates physical premises and property exposure from professional advice risk and digital records — not every professional office needs every coverage line, but most need clarity on how these pieces fit together.
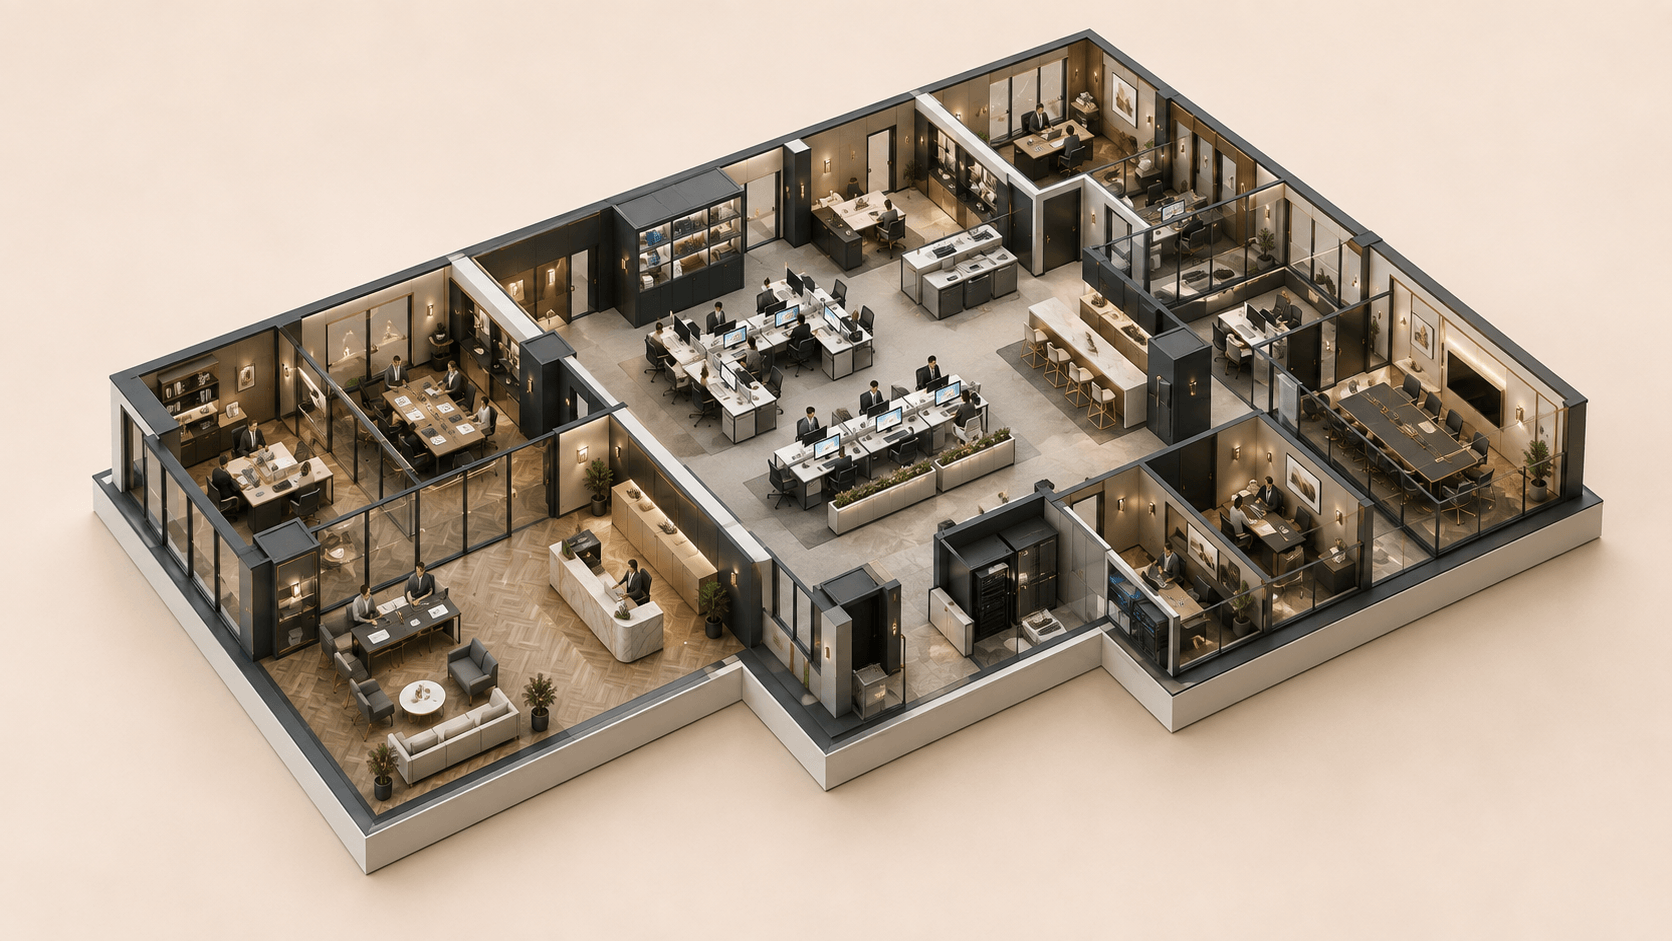
A client visit creates premises exposure separate from your advice: Waiting areas, conference rooms, washrooms, and parking access generate slip-and-fall and property-damage exposure when clients, couriers, or vendors come to you. General liability may address certain operational and premises claims, but allegations that your professional advice caused a financial loss are typically evaluated under professional liability — not ordinary CGL. Disclose whether staff also work at client sites or host off-site meetings.
A client visit creates premises exposure separate from your advice
Waiting areas, conference rooms, washrooms, and parking access generate slip-and-fall and property-damage exposure when clients, couriers, or vendors come to you. General liability may address certain operational and premises claims, but allegations that your professional advice caused a financial loss are typically evaluated under professional liability — not ordinary CGL. Disclose whether staff also work at client sites or host off-site meetings.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Professional offices FAQ
Straight answers to common questions for this industry.
There is no single standard package — most programs combine commercial general liability and commercial property for the premises and contents, then add professional liability and cyber coverage where the firm's services and data exposures warrant them. A purely administrative office with no professional services to clients may need GL and property only; a consulting or design office typically needs E&O as well. Your broker structures coverage to your lease, services, and contract requirements rather than selling every line to every office.
Ready when you are
Ready to cover your professional practice?
Tell us about your office, services, lease, and contract requirements — we'll compare options that fit how your practice actually operates.