
Commercial Insurance · Windsor-Essex
Convenience Store & Gas Station Insurance
Convenience stores and gas bars combine high-traffic retail, cash handling, and — at many locations — fuel dispensing, refrigerated inventory, and optional product lines such as lottery, tobacco, prepared food, or AGCO-authorized retail alcohol. Insurance needs reflect that mix: commercial property for the building and stock, general liability for customer incidents, pollution coverage where underground storage tanks create environmental exposure, and crime coverage where robbery and theft are material risks — each subject to the policies you purchase. Not every c-store sells alcohol, operates fuel pumps, or carries the same inventory profile. Premium Insurance Brokers can help map coverage to your hours, security practices, and actual product mix.
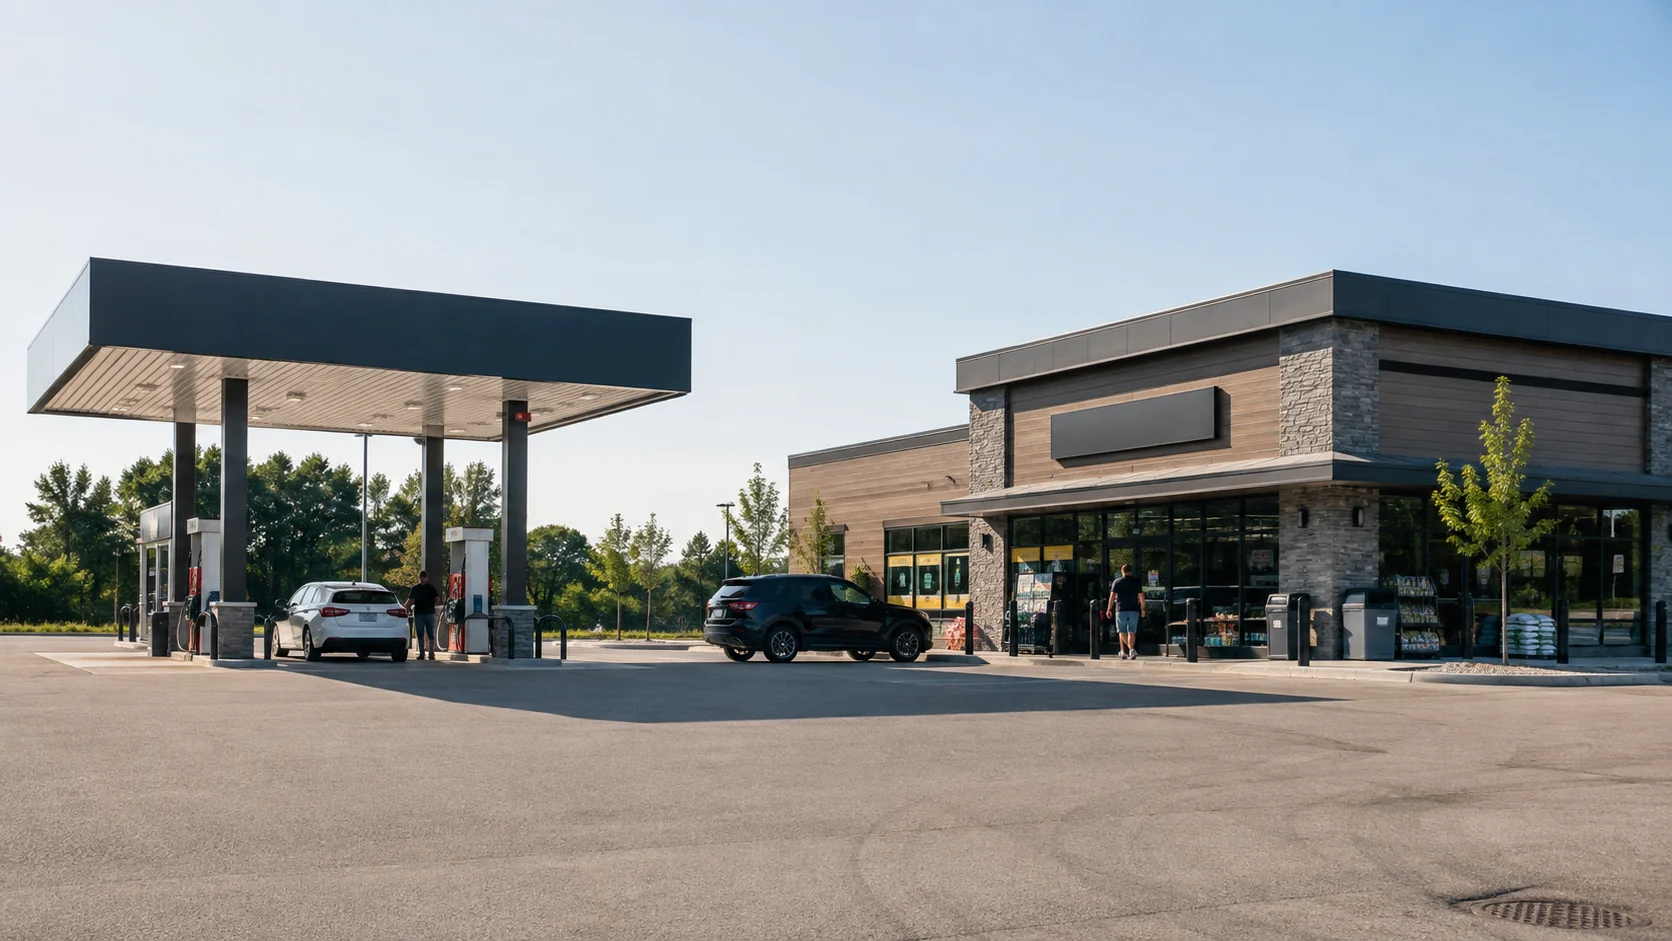
For Windsor–Essex independent convenience stores, gas bars, and combination fuel-and-retail operators — reviewed through an independent broker who can coordinate property, liability, pollution, and crime coverage for how you actually operate.
What's covered
Convenience and gas-bar insurance usually combines property protection for the building and inventory, liability for customer incidents on the sales floor and pump island, and — where relevant — pollution coverage for fuel tanks and crime coverage for cash and theft exposure.
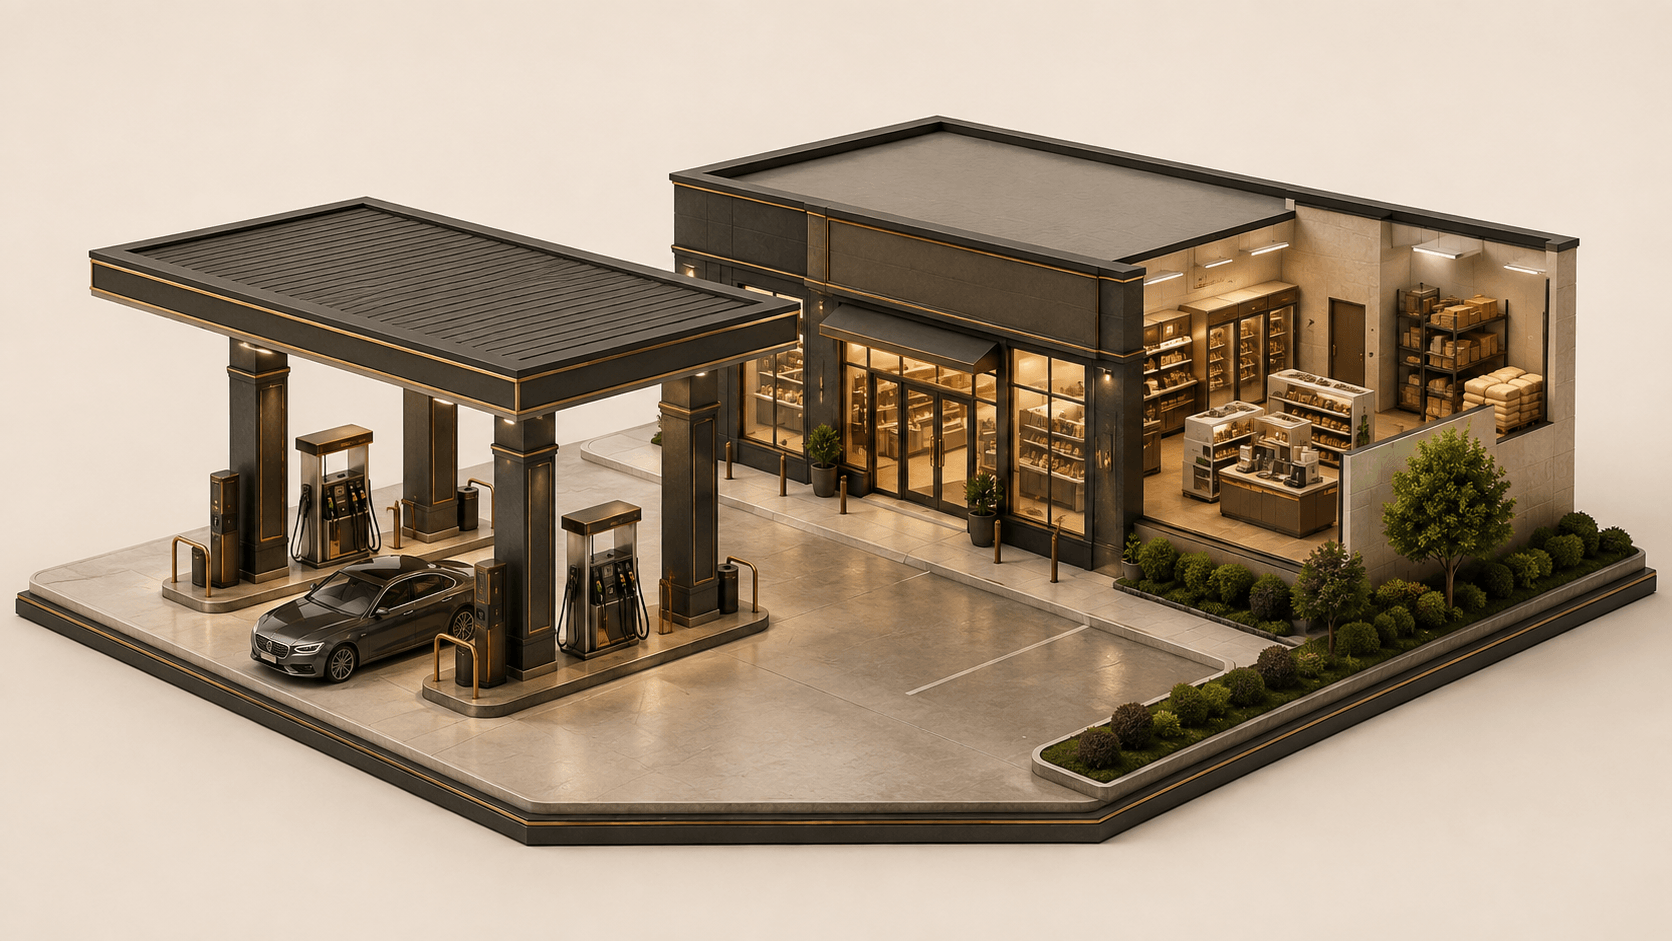
Coolers, inventory, and late-night theft drive property values: C-stores concentrate value in refrigerated and frozen inventory, general merchandise, and store fixtures — with higher theft exposure during extended or 24-hour hours. Inventory coverage depends on reported values, security requirements in the policy, and scheduled causes of loss. Stores that sell lottery products, tobacco, prepared food, or AGCO-authorized retail alcohol create additional underwriting questions separate from a generic retail property form — disclose your actual product mix to your broker.
Coolers, inventory, and late-night theft drive property values
C-stores concentrate value in refrigerated and frozen inventory, general merchandise, and store fixtures — with higher theft exposure during extended or 24-hour hours. Inventory coverage depends on reported values, security requirements in the policy, and scheduled causes of loss. Stores that sell lottery products, tobacco, prepared food, or AGCO-authorized retail alcohol create additional underwriting questions separate from a generic retail property form — disclose your actual product mix to your broker.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Convenience store FAQ
Straight answers to common questions.
Pump equipment, canopies, and related fixtures may be scheduled under commercial property coverage depending on how the policy is structured — subject to causes of loss, limits, and deductibles. Underground storage tanks and environmental contamination are typically addressed separately through pollution liability coverage, where purchased. Disclose whether you own, lease, or operate fuel equipment to your broker.
Ready when you are
Run a c-store or gas bar?
Tell us about fuel operations, inventory, and hours — we will compare retail and pollution coverage.