
Commercial Insurance · Windsor-Essex
Retail Insurance
Ordinary storefront retail — clothing boutiques, gift shops, electronics stores, furniture and home-goods shops, and specialty retailers — combines premises liability, stock and fixture values, and product-related claims in a package that differs from food retail, pharmacy, convenience, or fuel operations. Depending on your store, that can mean commercial general liability for customer incidents on the sales floor, commercial property for fixtures, equipment, and inventory, optional business interruption after a covered physical loss, and products liability for goods you sell or distribute — each subject to the policies you purchase. Not every shop sells online, carries high-theft inventory, or needs the same crime or cyber endorsements. Premium Insurance Brokers can help Windsor–Essex retailers align coverage to your actual merchandise, lease, and sales channels.
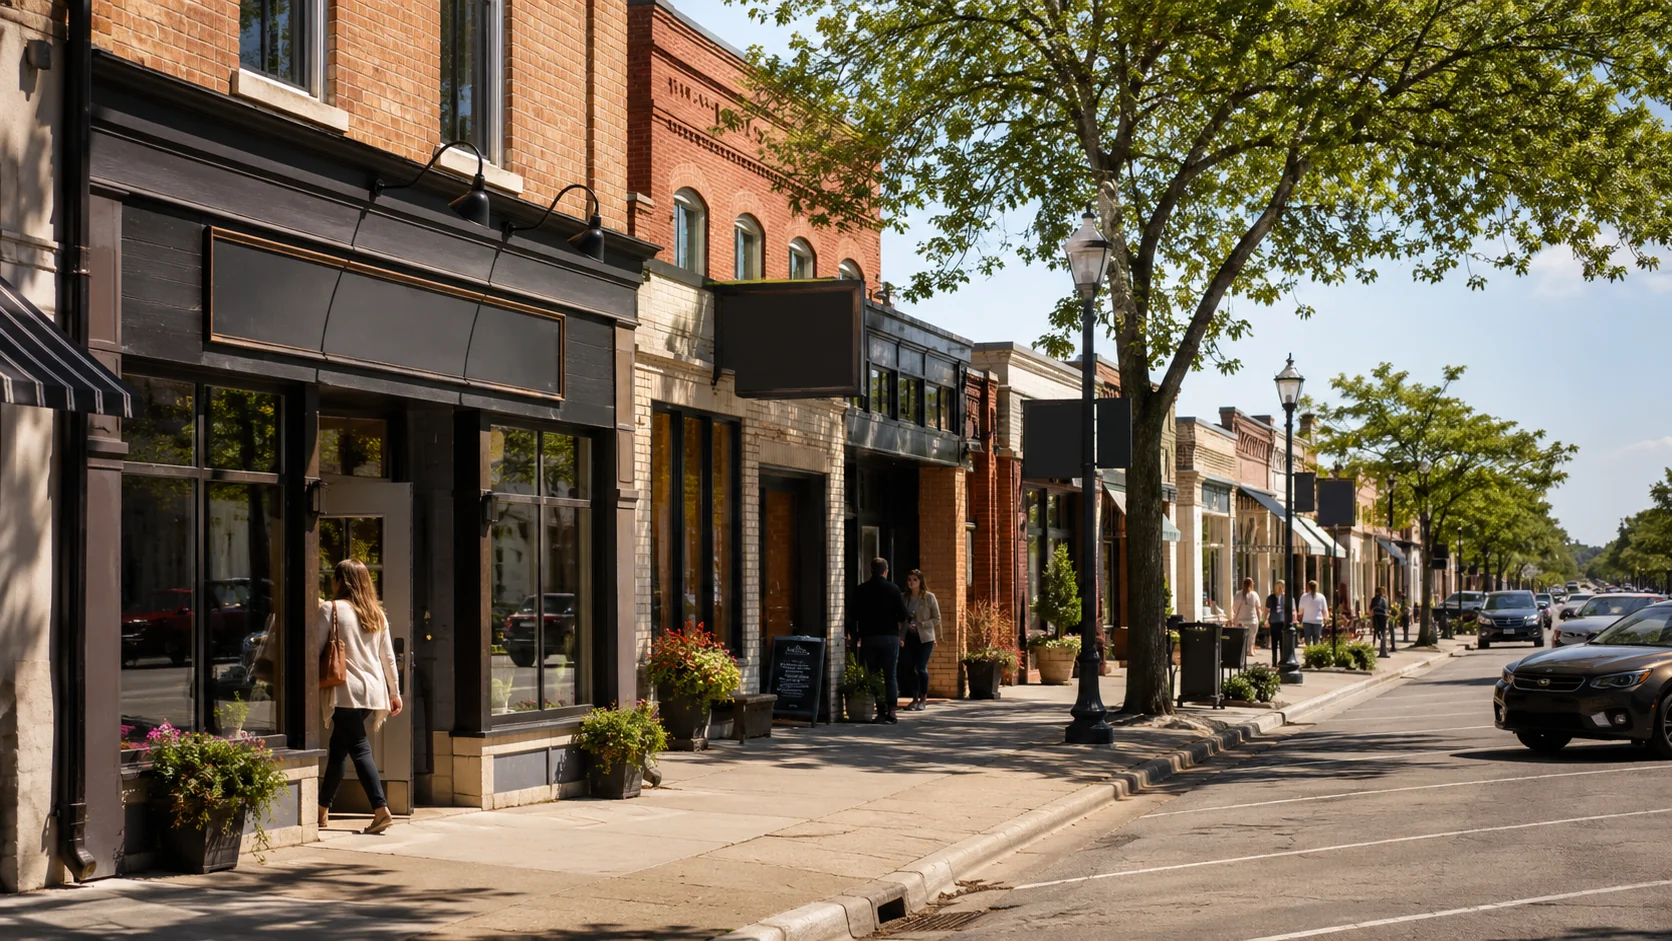
For Windsor–Essex clothing stores, gift shops, electronics retailers, furniture and home-goods shops, and other ordinary storefront retailers — reviewed through an independent broker who can coordinate liability, property, inventory, and optional crime or cyber coverage for how you actually sell.
What's covered
Retail insurance is usually organized around four exposures most storefront operators share — customer liability, property and stock, income after a covered loss, and products you sell — with optional crime, cyber, and delivery coverage reviewed separately where your operation needs them.
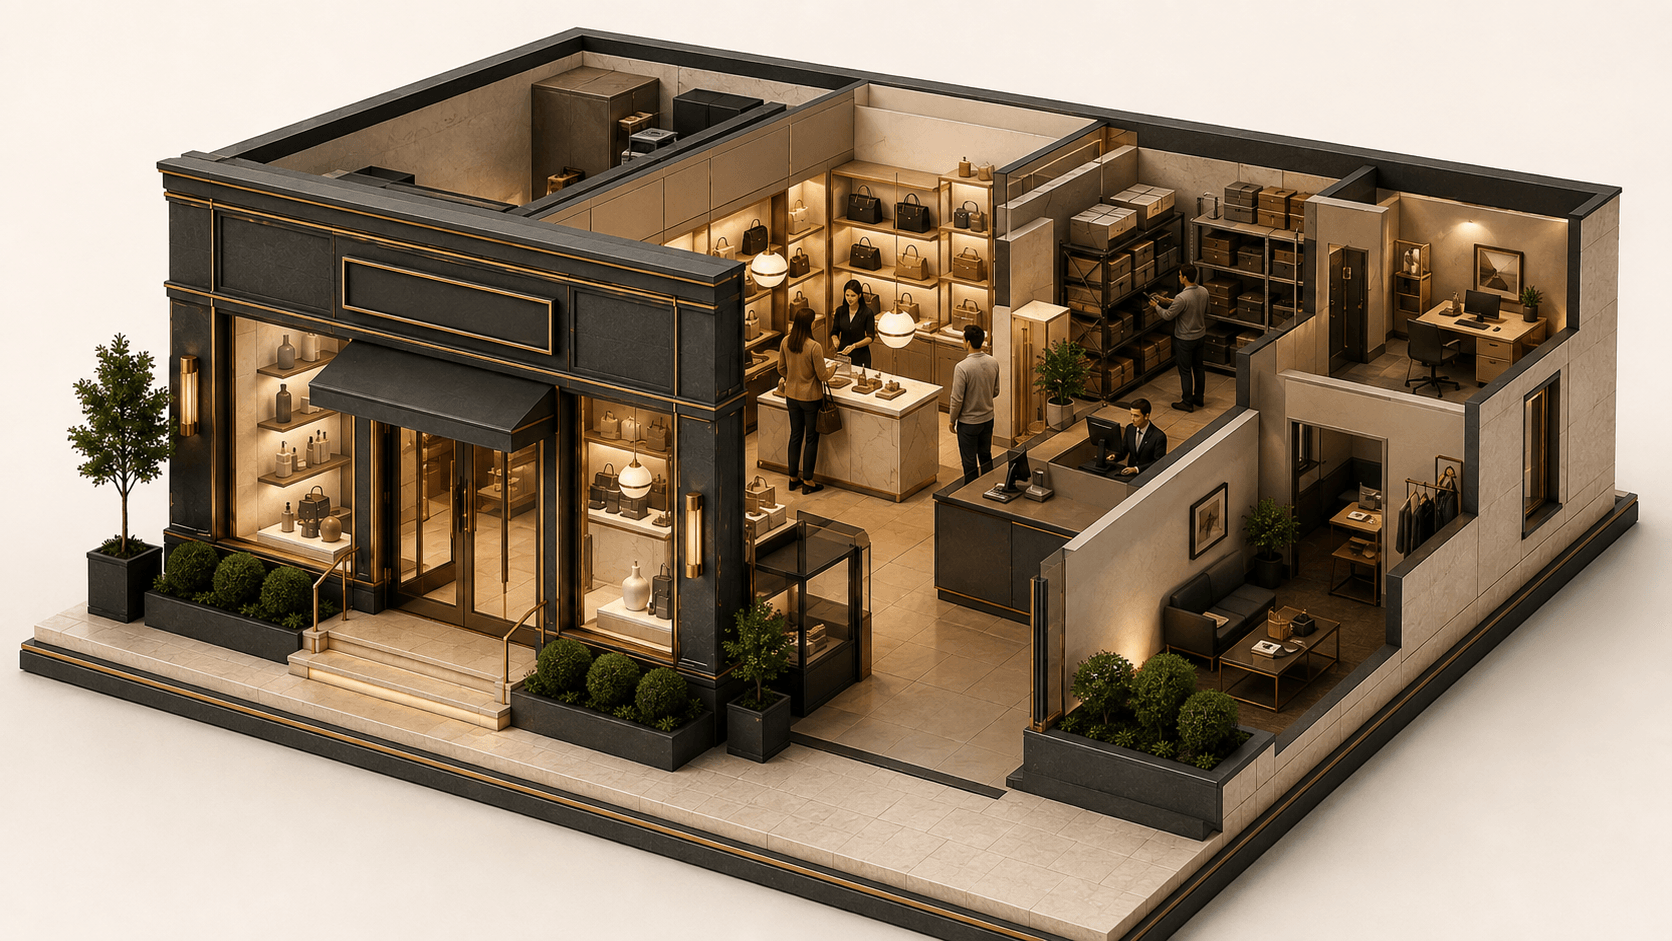
A wet entrance isn't just housekeeping: Retail premises exposure concentrates at entrances, fitting rooms, stockrooms open to staff traffic, and parking areas — especially in winter when tracked-in moisture and salt create slip hazards. Tenant legal liability for damage to leased premises may be available where endorsed. Product-related injury claims from something you sold are typically addressed under products liability rather than premises coverage — the policy part depends on how the claim is framed and what was disclosed during underwriting.
A wet entrance isn't just housekeeping
Retail premises exposure concentrates at entrances, fitting rooms, stockrooms open to staff traffic, and parking areas — especially in winter when tracked-in moisture and salt create slip hazards. Tenant legal liability for damage to leased premises may be available where endorsed. Product-related injury claims from something you sold are typically addressed under products liability rather than premises coverage — the policy part depends on how the claim is framed and what was disclosed during underwriting.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Retail insurance FAQ
Straight answers to common questions for this industry.
Most Windsor–Essex storefront retailers start with commercial general liability and commercial property for premises and stock — then add business interruption, crime, cyber, or product-specific endorsements depending on inventory values, online sales, and contract requirements. Each component is subject to the policies you purchase; a quote description is not a guarantee every coverage type is included until confirmed on your binder.
Ready when you are
Ready to cover your retail business?
Tell us about your storefront, stock, and sales channels — we will compare retail programs that fit.