
Commercial Insurance · Windsor-Essex
Cannabis Retail Insurance
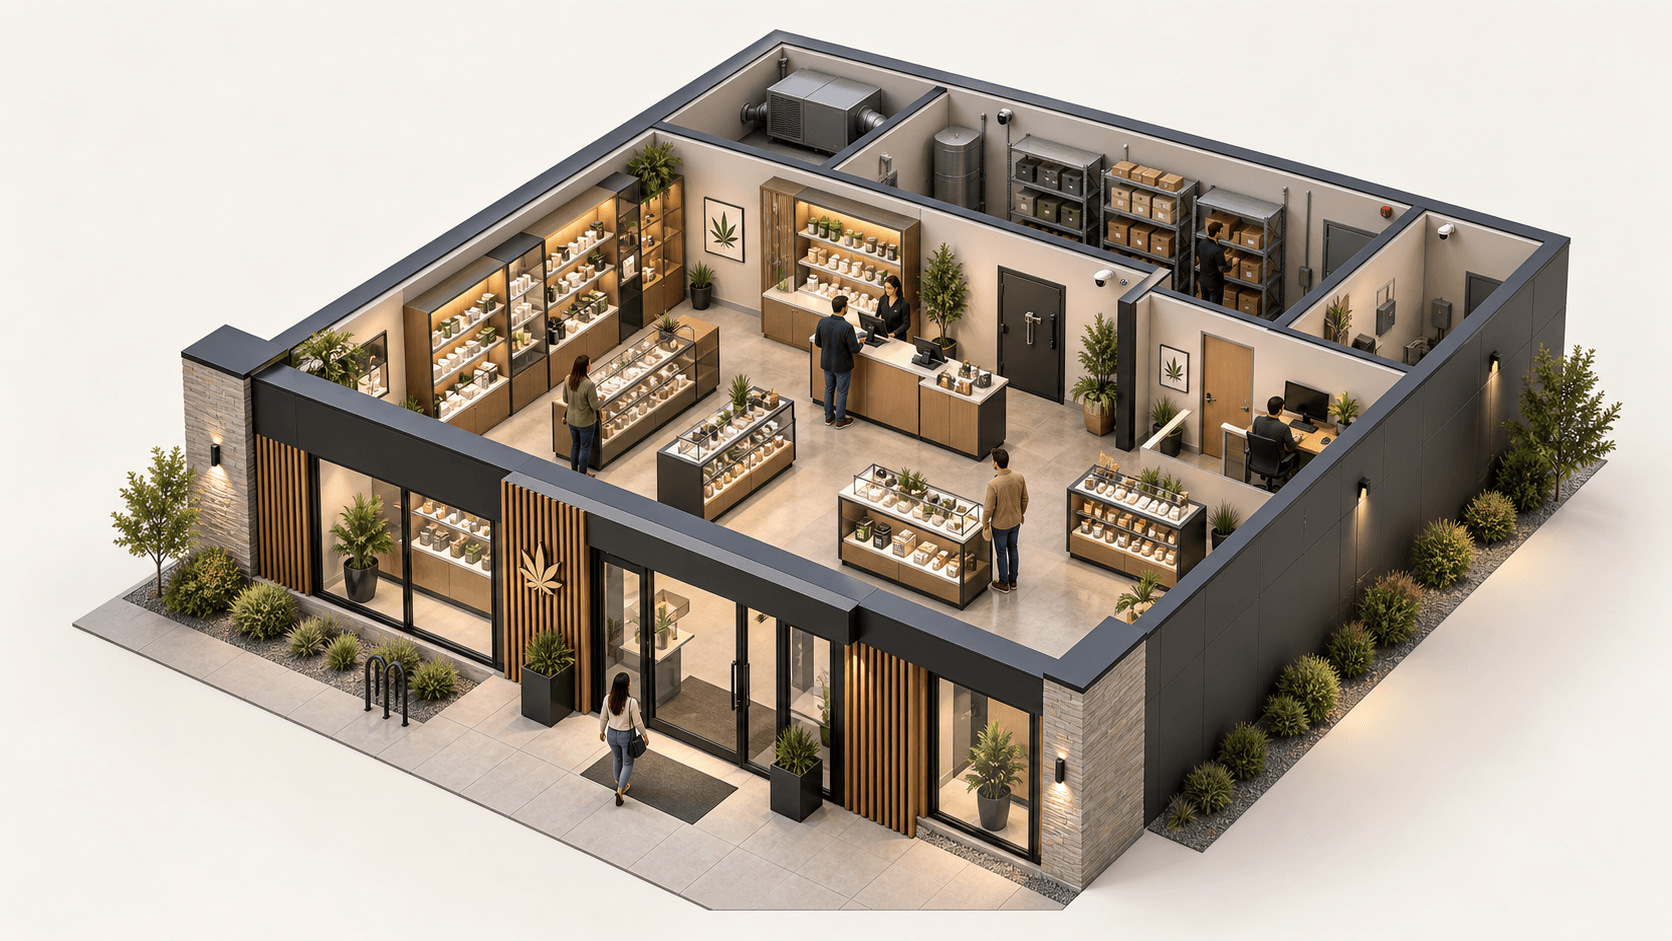
Ontario authorized cannabis retail stores combine storefront liability, high-value packaged inventory, landlord and Ontario Cannabis Store (OCS) contract requirements, and theft exposure in a way that differs from ordinary retail. Coverage is organized around how your store actually operates — premises and general liability, property and cannabis stock, product liability, crime, and business interruption where purchased — each subject to the policies and wording you buy. AGCO licensing regulates the store; it is not the same thing as an insurance policy. Premium Insurance Brokers can help Windsor–Essex cannabis retailers review programs against lease, security, and wholesale-contract expectations.
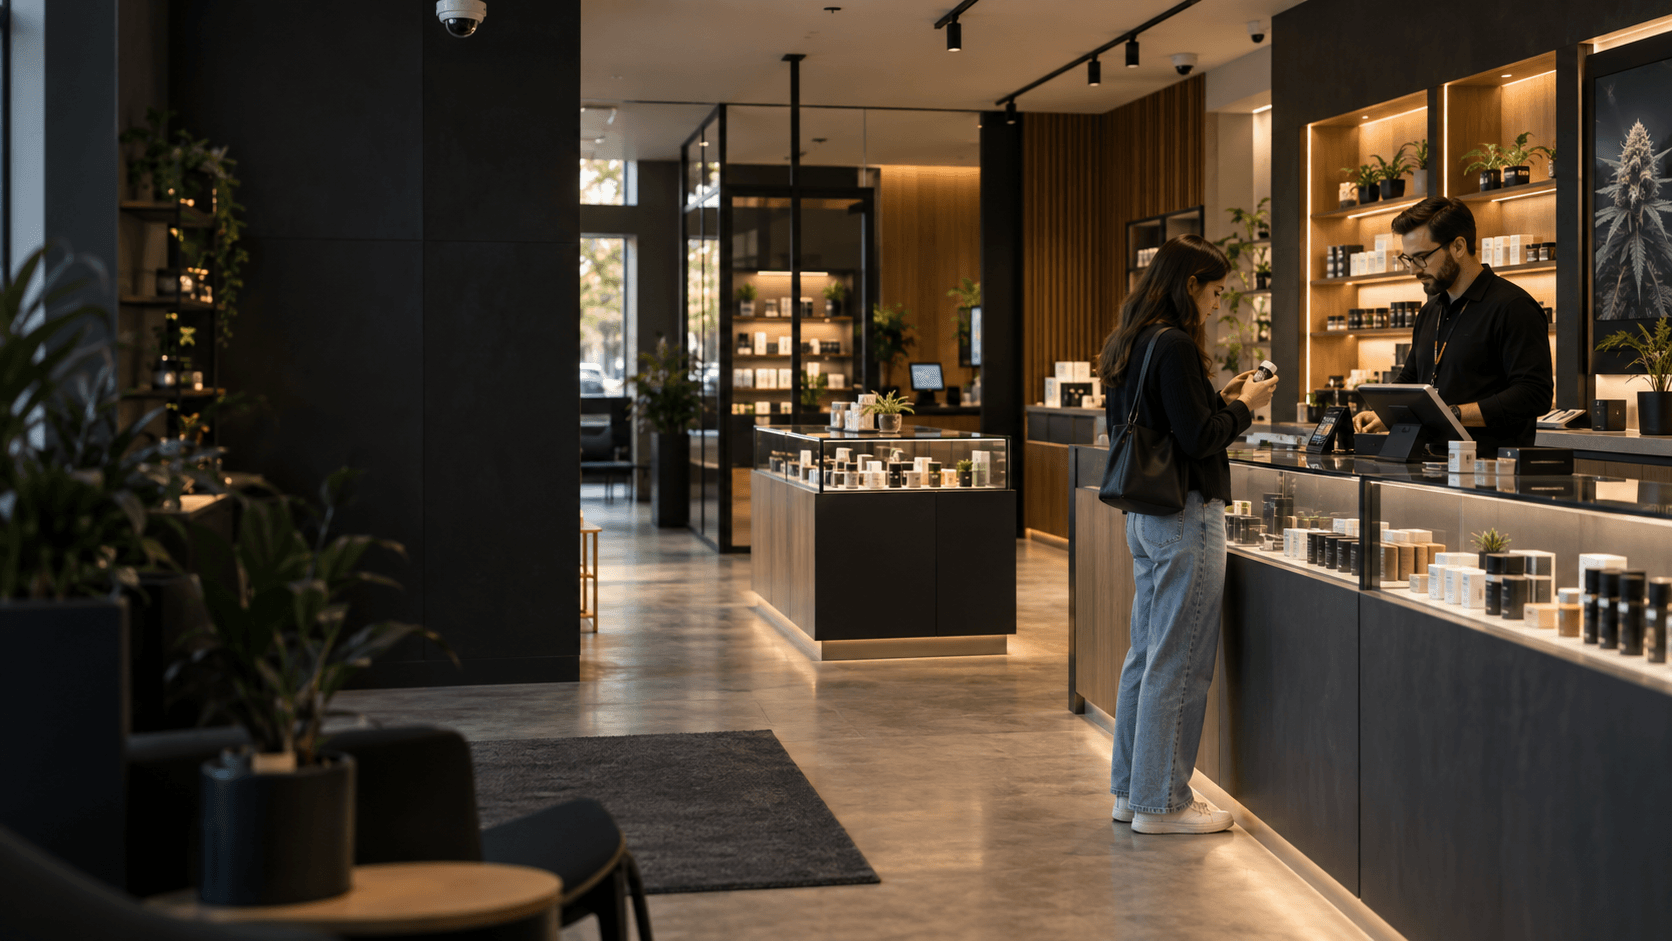
For Windsor–Essex and Ontario operators of AGCO-authorized cannabis retail stores — reviewed through an independent broker who can coordinate liability, property and stock, product liability, crime, and business interruption against lease and OCS contract expectations.
What's covered
Cannabis retail insurance is grouped here around five storefront exposures Ontario operators commonly review first — premises liability, property and stock, product liability, crime, and income after a covered physical loss — because each agreement has different triggers, limits, and exclusions.
A slip at the entrance is a premises claim — not a licensing issue: Authorized cannabis stores still face ordinary retail premises exposure: winter entrances, sales-floor traffic, ID-check queues, and parking areas. Commercial general liability may address certain covered third-party injury or property-damage claims subject to wording — it does not replace AGCO compliance, and it does not automatically satisfy every landlord or OCS contractual insurance schedule. Additional-insured requests and limit requirements should be compared to the certificate your policy can actually support.
A slip at the entrance is a premises claim — not a licensing issue
Authorized cannabis stores still face ordinary retail premises exposure: winter entrances, sales-floor traffic, ID-check queues, and parking areas. Commercial general liability may address certain covered third-party injury or property-damage claims subject to wording — it does not replace AGCO compliance, and it does not automatically satisfy every landlord or OCS contractual insurance schedule. Additional-insured requests and limit requirements should be compared to the certificate your policy can actually support.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Cannabis retail insurance FAQ
Straight answers to common questions for this industry.
Most authorized stores review commercial general liability, commercial property for improvements and stock, product liability, crime, and business interruption where income protection is needed after a covered physical loss. Landlord and OCS contract schedules may add specific limit or additional-insured requirements. Exact components depend on the policies you purchase — there is no single automatic cannabis retail package.
Ready when you are
Ready to review cannabis retail coverage?
Share your store authorization status, lease insurance schedule, security controls, and inventory profile — we will compare markets and explain what may fit, subject to underwriting.