
Commercial Insurance · Windsor-Essex
Pharmacy Insurance
Pharmacies combine professional dispensing exposure, high-value prescription inventory, refrigerated stock, and sensitive patient health information — a different risk profile from ordinary retail. Depending on your operation, that can mean commercial property for fixtures, equipment, and stock; general liability for customer incidents on your premises; professional liability or errors and omissions for certain dispensing and counselling-related claims at the business level; and cyber or privacy coverage where purchased for data-breach response — each subject to the policies you purchase. Ontario pharmacists must maintain personal professional liability insurance under OCP requirements separately from the pharmacy's business insurance program. Premium Insurance Brokers can help align coverage to your dispensing model, cold-chain setup, services, and security practices.
For Windsor–Essex independent pharmacies, compounding pharmacies, and retail drug stores — reviewed through an independent broker who can coordinate property, premises liability, professional dispensing coverage, and cyber/privacy protection for how you actually dispense, store, and protect patient information.
What's covered
Pharmacy insurance usually separates premises and property exposure from professional dispensing liability and patient-data risks — depending on your prescription volume, clinical services, refrigeration, delivery model, and how your business policy coordinates with registrants' OCP personal professional liability insurance.
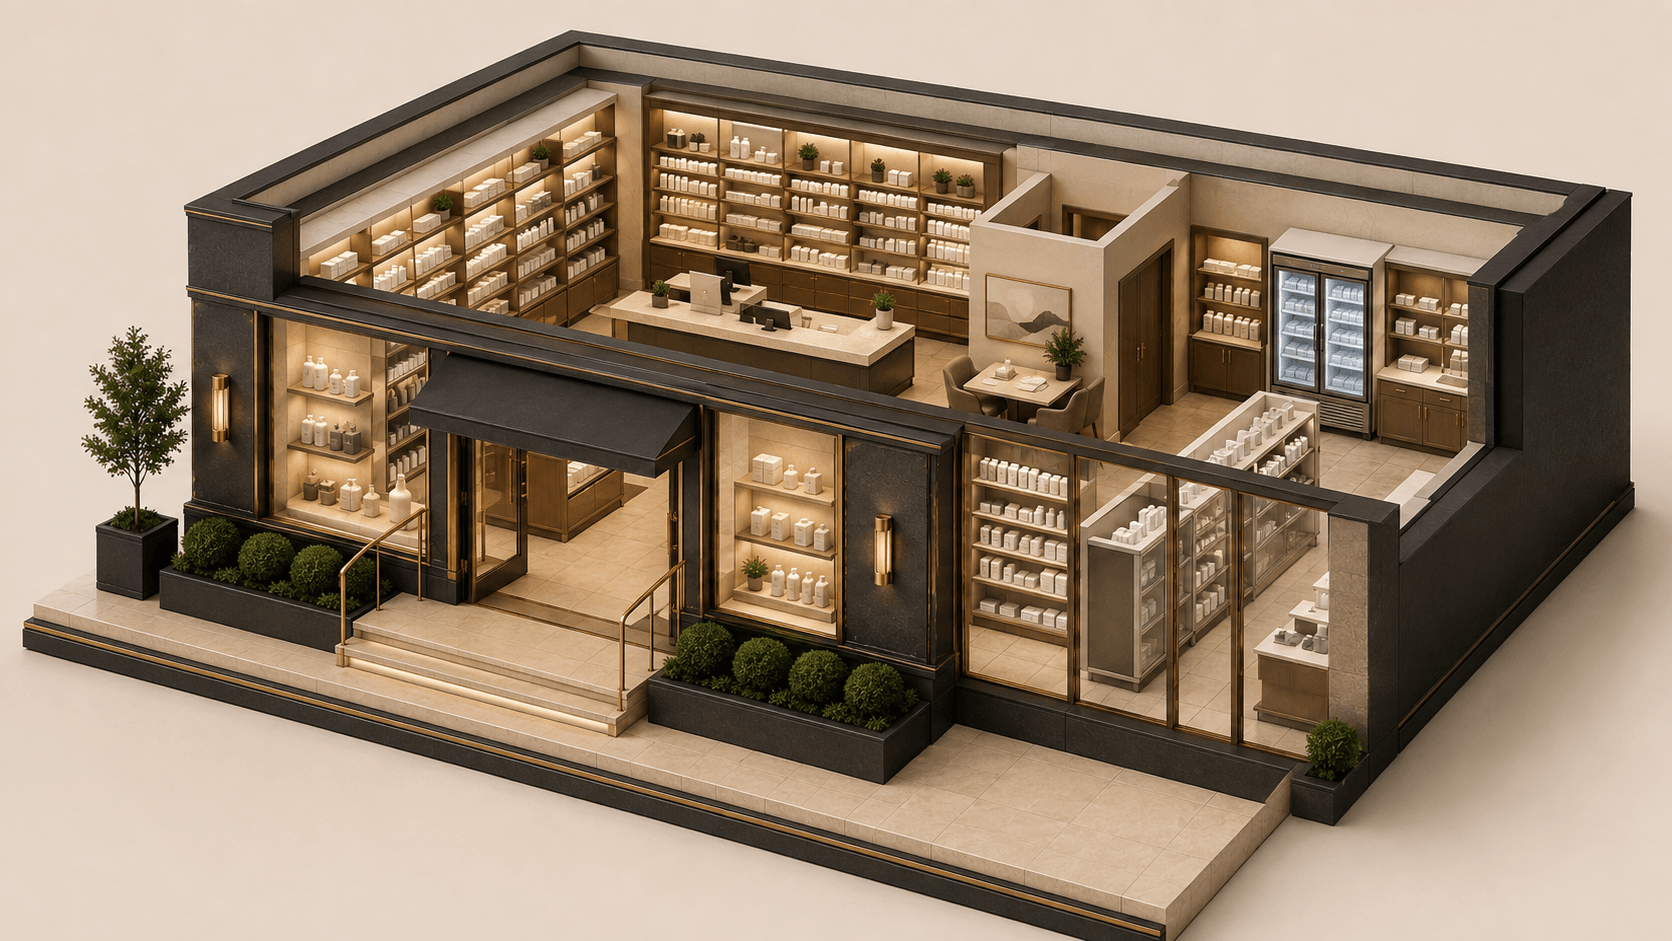
Prescription inventory and cold-chain equipment drive property values: Pharmacy property exposure concentrates in dispensary fixtures, automation, compounding equipment, and prescription stock — including high-value and refrigerated medications. Base commercial property may address certain physical damage or theft subject to policy wording, but temperature-related stock loss from equipment failure, power interruption, or utility outage is often treated differently from fire or burglary — equipment breakdown, spoilage, or deterioration endorsements may be needed depending on cause of loss and policy structure. Do not assume refrigerated inventory is fully covered without reviewing triggers, sublimits, and backup-power disclosures with your broker.
Prescription inventory and cold-chain equipment drive property values
Pharmacy property exposure concentrates in dispensary fixtures, automation, compounding equipment, and prescription stock — including high-value and refrigerated medications. Base commercial property may address certain physical damage or theft subject to policy wording, but temperature-related stock loss from equipment failure, power interruption, or utility outage is often treated differently from fire or burglary — equipment breakdown, spoilage, or deterioration endorsements may be needed depending on cause of loss and policy structure. Do not assume refrigerated inventory is fully covered without reviewing triggers, sublimits, and backup-power disclosures with your broker.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Pharmacy insurance FAQ
Straight answers to common questions.
Generally no — or not as a standard premises claim. Allegations involving the wrong drug, strength, patient, directions, or counselling are typically evaluated as professional liability or errors and omissions exposure, separate from slip-and-fall or other third-party injury claims general liability may address. Pharmacy business professional coverage and each registrant's OCP personal professional liability insurance serve different roles — confirm how your program structures professional allegations with your broker.
Ready when you are
Own or operate a pharmacy?
Share prescription volume, services, refrigeration setup, and security practices — we will compare pharmacy coverage options.