
Commercial Insurance · Windsor-Essex
Event Liability Insurance
Event liability insurance addresses third-party injury and property-damage claims arising from a specific event you host — weddings, festivals, fundraisers, corporate functions, or vendor markets — on defined dates and at stated locations. It is not a substitute for a venue owner's policy, your own property coverage for equipment, or cancellation insurance for weather or low attendance. Venues, municipalities, and rental contracts often require proof of liability insurance with minimum limits or additional-insured wording — those are contractual requirements, not a single provincial event-insurance mandate. Where alcohol is served under a Special Occasion Permit or host-liquor arrangement, liquor-related liability may need separate review. Premium Insurance Brokers can help structure coverage to match your event type, attendance, activities, and certificate requirements.
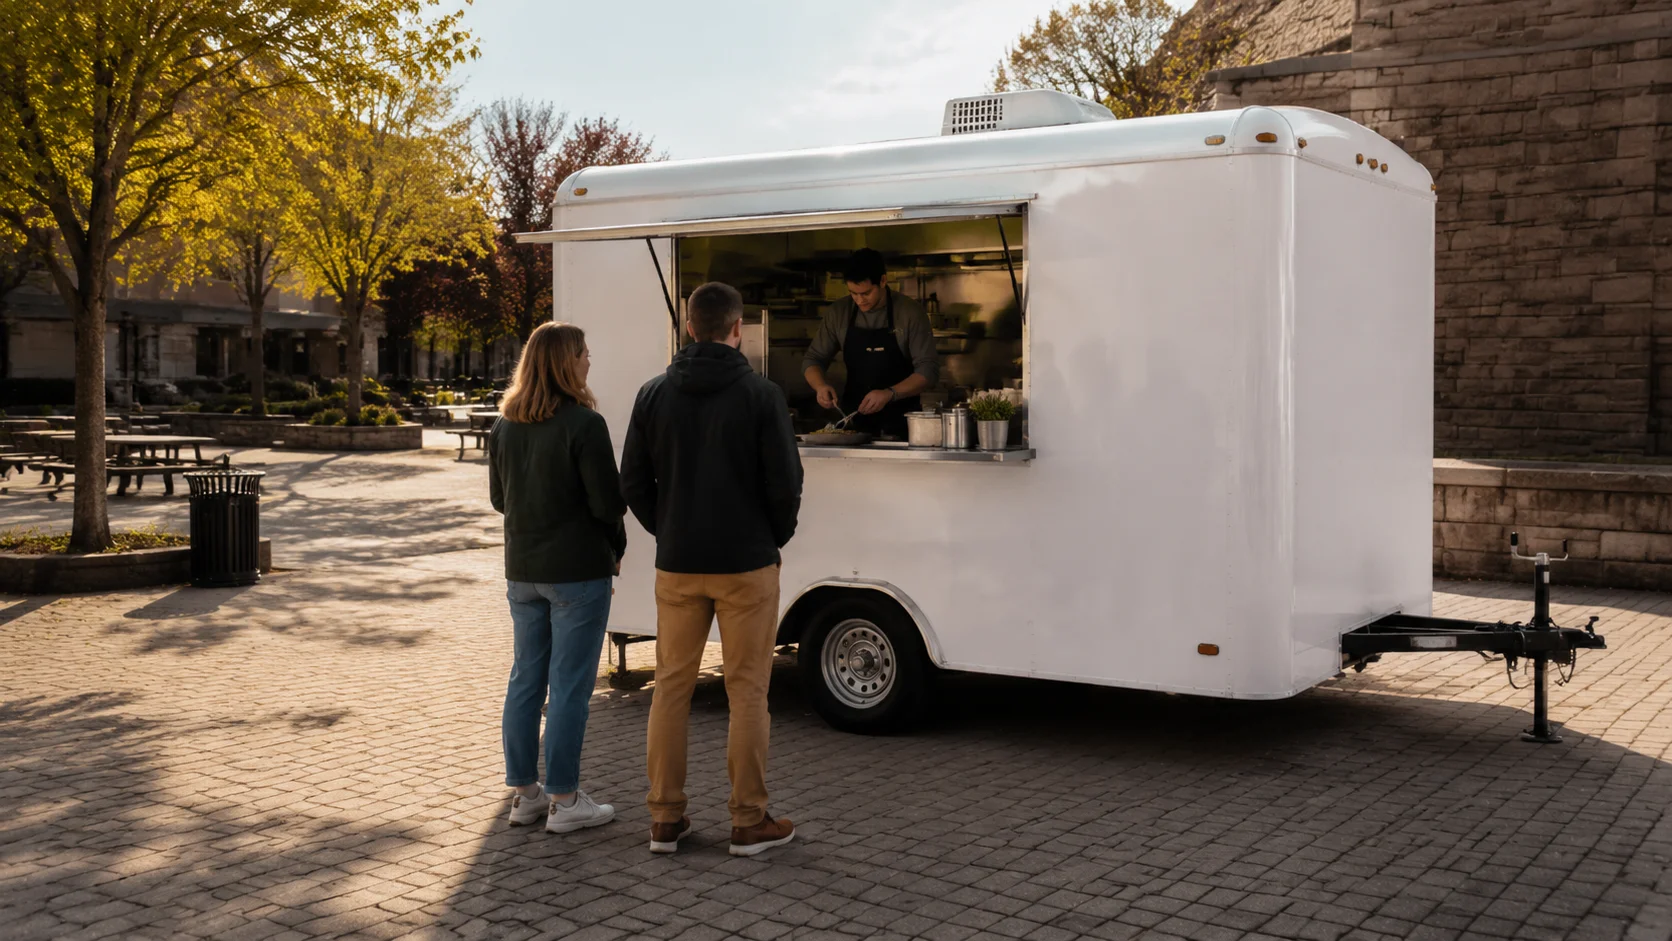
For Windsor–Essex event organizers, wedding hosts, festival committees, farmers' market operators, and vendors when venues or permits require certificates — reviewed through an independent broker who can align short-term liability coverage to your event dates, activities, and contractual requirements.
What's covered
Event liability focuses on third-party bodily injury and property-damage claims tied to a defined event — separate from ongoing business insurance, venue policies that protect the property owner, and optional products such as cancellation or own-equipment coverage.
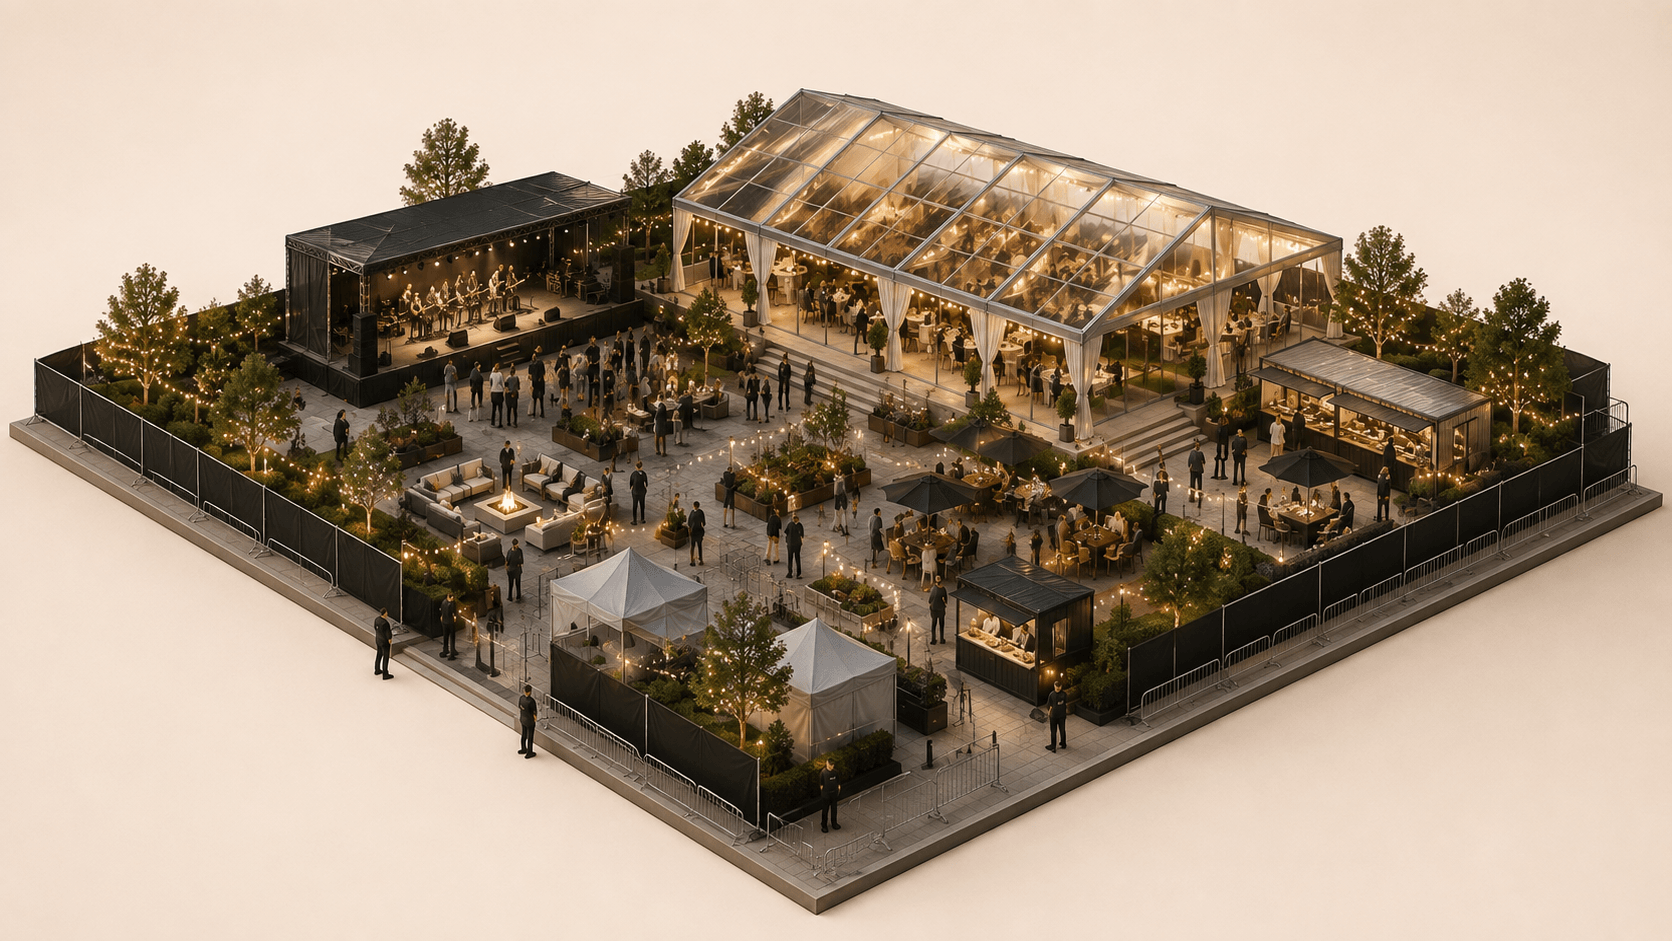
A wedding reception trip-and-fall is an event-host exposure: Temporary events concentrate people in unfamiliar layouts — tents, dance floors, vendor aisles, staging, and parking areas — where trips, falls, and crowd incidents can generate third-party injury claims against the event host. Event liability policies are written for defined dates, locations, and attendance; whether a specific activity, amusement device, or sporting element is covered depends on policy wording and what you disclosed during underwriting. This coverage addresses host liability — not the venue owner's own policy, which protects the venue's interests.
A wedding reception trip-and-fall is an event-host exposure
Temporary events concentrate people in unfamiliar layouts — tents, dance floors, vendor aisles, staging, and parking areas — where trips, falls, and crowd incidents can generate third-party injury claims against the event host. Event liability policies are written for defined dates, locations, and attendance; whether a specific activity, amusement device, or sporting element is covered depends on policy wording and what you disclosed during underwriting. This coverage addresses host liability — not the venue owner's own policy, which protects the venue's interests.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Event liability FAQ
Straight answers to common questions.
Event policies are often written for specific dates, locations, setup and teardown periods, and defined attendance — subject to underwriting review. Short-term event liability is distinct from an ongoing commercial general liability policy for a permanent business. Confirm effective dates and any activity restrictions with your broker before the event.
Ready when you are
Planning an event?
Share event date, location, attendance, and activities — we will help structure liability coverage around your event and venue certificate requirements.