
Commercial Insurance · Windsor-Essex
Non-Profit Insurance
Charities and non-profits combine program delivery, volunteer involvement, and board governance into exposures that differ from a typical small business — even when the day-to-day work looks similar. Depending on your organization, that can mean general liability for events and program locations, directors and officers coverage for governance claims, property coverage for office contents and donated goods, volunteer accident coverage where purchased, and — for programs serving children or vulnerable persons — abuse or misconduct coverage reviewed separately. Not every non-profit needs the same coverage stack; a community sports league, a social service agency, and a grant-making foundation face different profiles. Premium Insurance Brokers can help align insurance to your programs, funding requirements, and governance structure.
For Windsor–Essex charities, foundations, community organizations, and social-service agencies — reviewed through an independent broker who can coordinate liability, governance, property, and program-specific coverage for how you actually operate.
What's covered
Non-profit insurance usually addresses premises and program liability, board governance exposure, property supporting your mission, and — where relevant — volunteer injury and abuse or misconduct coverage — depending on your programs, lease arrangements, and funder requirements.
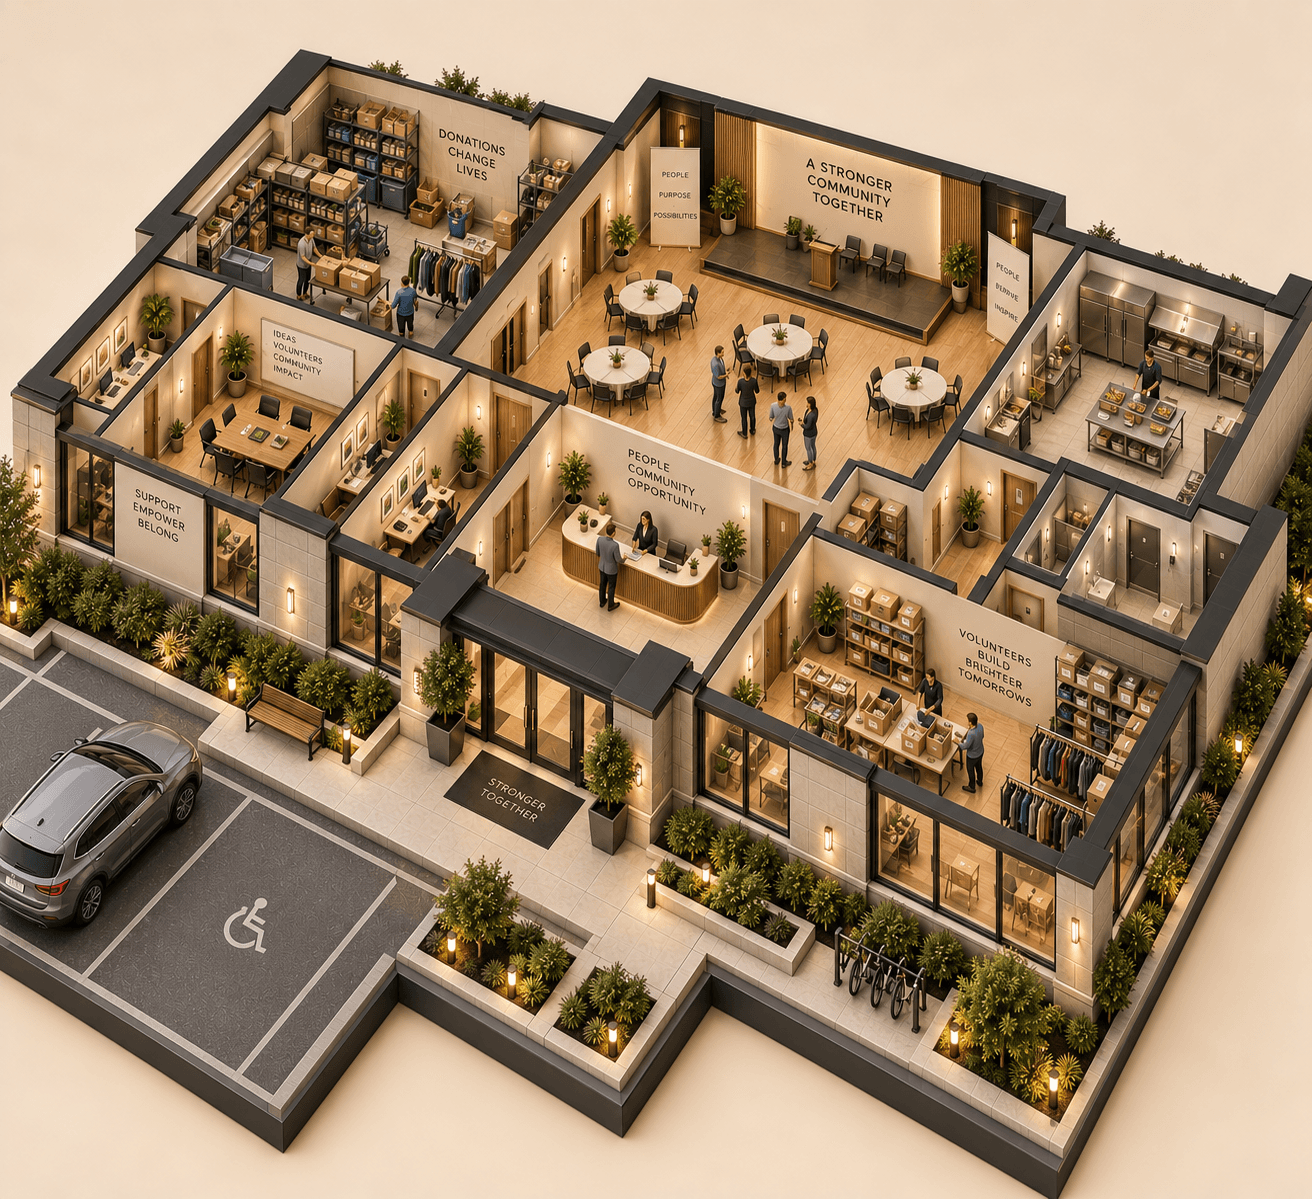
When a program participant injury becomes an organization claim: Community programs, fundraising events, food drives, and leased facility operations can generate third-party injury or property-damage claims against the organization — distinct from a board governance dispute or an employee injury covered elsewhere. Whether a specific event, off-site program, or volunteer activity is covered depends on policy wording and what was disclosed during underwriting. Funder and venue certificate requirements are contractual — separate from what any single policy automatically includes.
When a program participant injury becomes an organization claim
Community programs, fundraising events, food drives, and leased facility operations can generate third-party injury or property-damage claims against the organization — distinct from a board governance dispute or an employee injury covered elsewhere. Whether a specific event, off-site program, or volunteer activity is covered depends on policy wording and what was disclosed during underwriting. Funder and venue certificate requirements are contractual — separate from what any single policy automatically includes.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Non-profit FAQ
Straight answers to common questions.
Board-governed non-profits can face claims alleging governance or management failures — separately from general liability for program injury. D&O coverage, where purchased, may help respond to certain claims against directors and officers subject to policy terms. It does not eliminate statutory director duties under applicable corporate law. Many organizations carry D&O to support board recruitment, but the appropriate structure depends on your governance model.
Ready when you are
Lead a non-profit organization?
Tell us about your programs, volunteers, and board — we will compare nonprofit coverage options.