
Commercial Insurance · Windsor-Essex
Garage & Dealership Insurance
Garage and dealership insurance in Ontario usually layers the regulated Ontario Garage Automobile Policy (OAP 4) with commercial property and commercial general liability — because repair garages and vehicle dealers face different automobile, inventory, and premises exposures. OAP 4 addresses third-party automobile liability, statutory accident benefits, uninsured automobile, DCPD, optional physical damage on owned units, and legal liability for customer vehicles in your care, custody, or control — subject to sections purchased and policy wording. That is not interchangeable with a standard CGL policy alone or with ordinary commercial auto for a contractor's pickup. Dealers add open-lot inventory values, test drives, and floorplan interests; repair shops emphasize hoists, customer vehicles during service, and completed-operations liability. Licensed garage operations in Ontario typically must evidence a standard garage automobile policy as part of MTO licensing — separate from OMVIC's broader expectation that dealers maintain appropriate insurance without prescribing a specific limit in every case. Premium Insurance Brokers can help Windsor–Essex shops and dealers align OAP 4, property, and liability for how you actually operate.
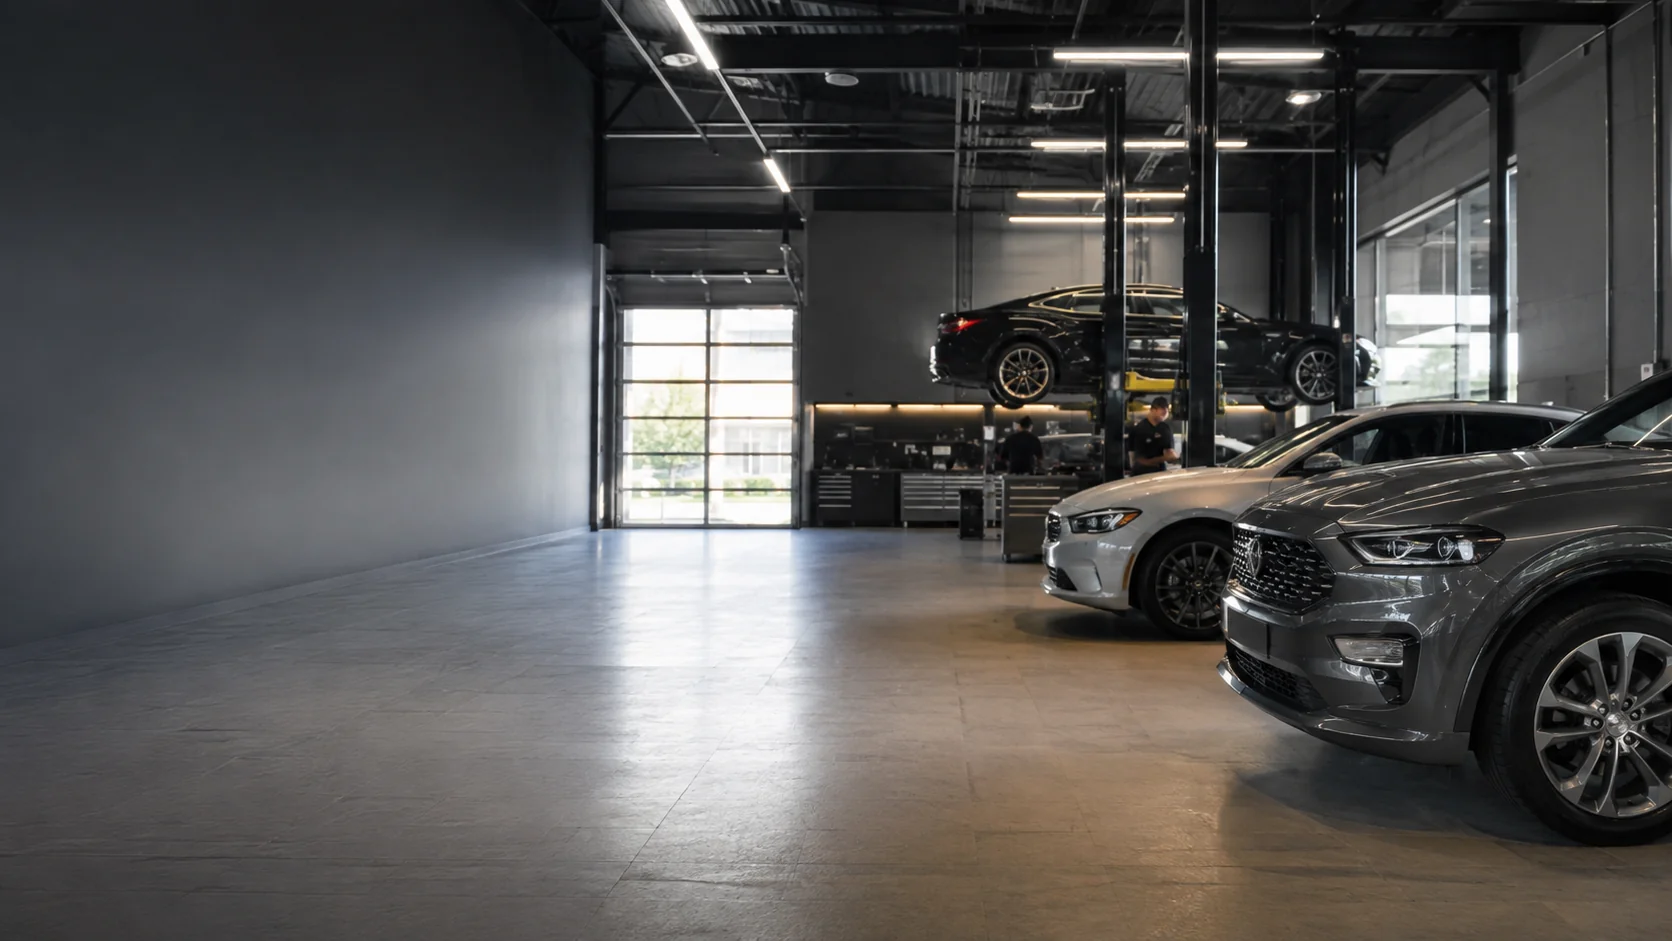
For Windsor–Essex repair garages, mechanics, body shops, tire and quick-lube centres, detailers, and new or used auto dealers that hold customer vehicles or inventory — reviewed through an independent broker who can distinguish OAP 4 garage automobile, property for tools and buildings, and operations liability for each operation type.
What's covered
Coverage for Ontario garage and dealership operations is organized here by garage automobile (OAP 4), customer-vehicle legal liability, dealer inventory and open lot, and operations liability — because dealers and repair shops share OAP 4 concepts but differ on inventory, test drives, and property exposures.
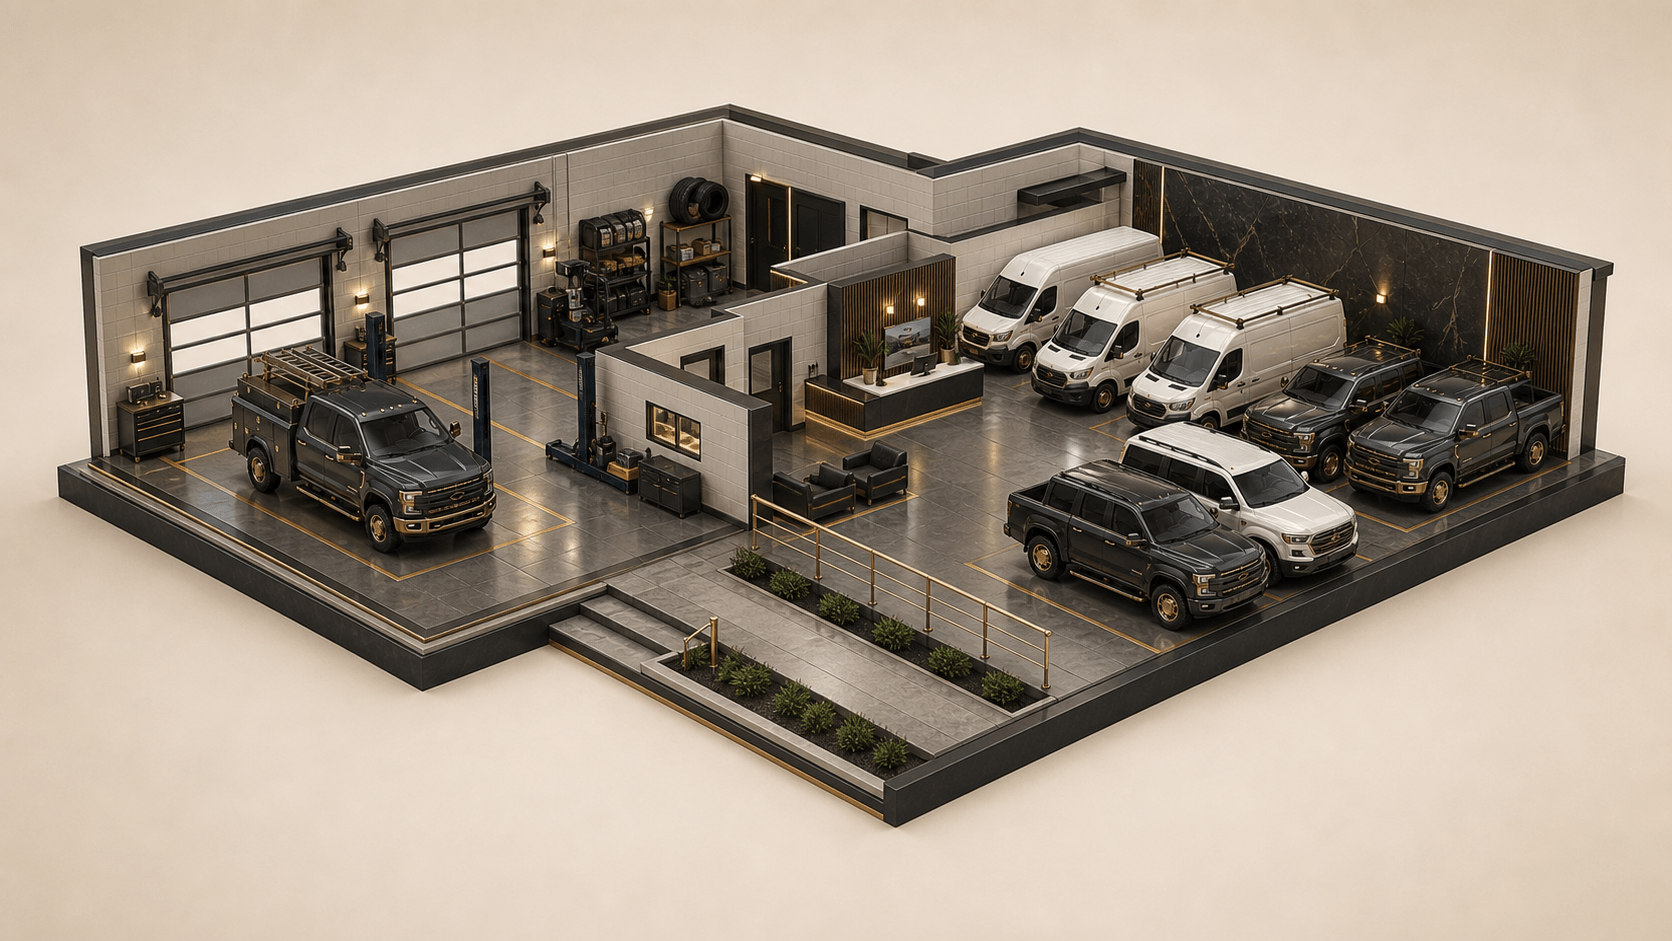
Customer cars are insured elsewhere first — your legal liability still matters: When a customer's vehicle is damaged in your bay, their own automobile insurer may pay first; your garage policy responds to your legal liability for the loss when the policy trigger and facts support it — not as a blanket guarantee on every scratch or lot incident. Legal-liability and direct-primary forms treat fault and payment order differently; confirm which structure your program uses. Limits, per-vehicle deductibles, and maximum values per occurrence are scheduled — inadequate limits leave the shop exposed after a total loss or multi-vehicle event.
Customer cars are insured elsewhere first — your legal liability still matters
When a customer's vehicle is damaged in your bay, their own automobile insurer may pay first; your garage policy responds to your legal liability for the loss when the policy trigger and facts support it — not as a blanket guarantee on every scratch or lot incident. Legal-liability and direct-primary forms treat fault and payment order differently; confirm which structure your program uses. Limits, per-vehicle deductibles, and maximum values per occurrence are scheduled — inadequate limits leave the shop exposed after a total loss or multi-vehicle event.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Garage & dealership FAQ
Straight answers to common questions.
Most repair and service garages need the Ontario Garage Automobile Policy (OAP 4) for automobile liability, statutory benefits, and — where purchased — legal liability for customer vehicles in care, custody, or control. Commercial property for the building, tools, and equipment, plus commercial general liability or a garage liability package for premises and completed-operations exposures, typically sit alongside OAP 4 — one policy does not replace the others. MTO garage licensing expects evidence of a standard garage automobile policy.
Ready when you are
Run a garage or dealership?
Tell us whether you repair, sell, or both — we will compare OAP 4, property, and liability programs for your operation.