
Commercial Insurance · Windsor-Essex
Manufacturing Insurance
Ordinary manufacturing and light industrial operations in Windsor–Essex — fabrication, machining, metalworking, plastics, assembly, and job-shop production — combine property values, production equipment, products liability, and income interruption risks that differ from retail, contracting, or warehouse-only businesses. Depending on your plant, that can mean commercial property for buildings, machinery, raw materials, work-in-progress, and finished goods; commercial general liability for certain third-party injury and property-damage claims tied to products you make; optional business interruption after a covered direct physical loss; and equipment breakdown coverage where purchased for internal mechanical or electrical failures not handled like fire or theft on a standard property form. Pollution, product recall expense, crime, and cyber may need separate review when exposures are material — not every manufacturer needs every specialty line on day one. Premium Insurance Brokers can help align limits to how you actually produce, stock, and ship.
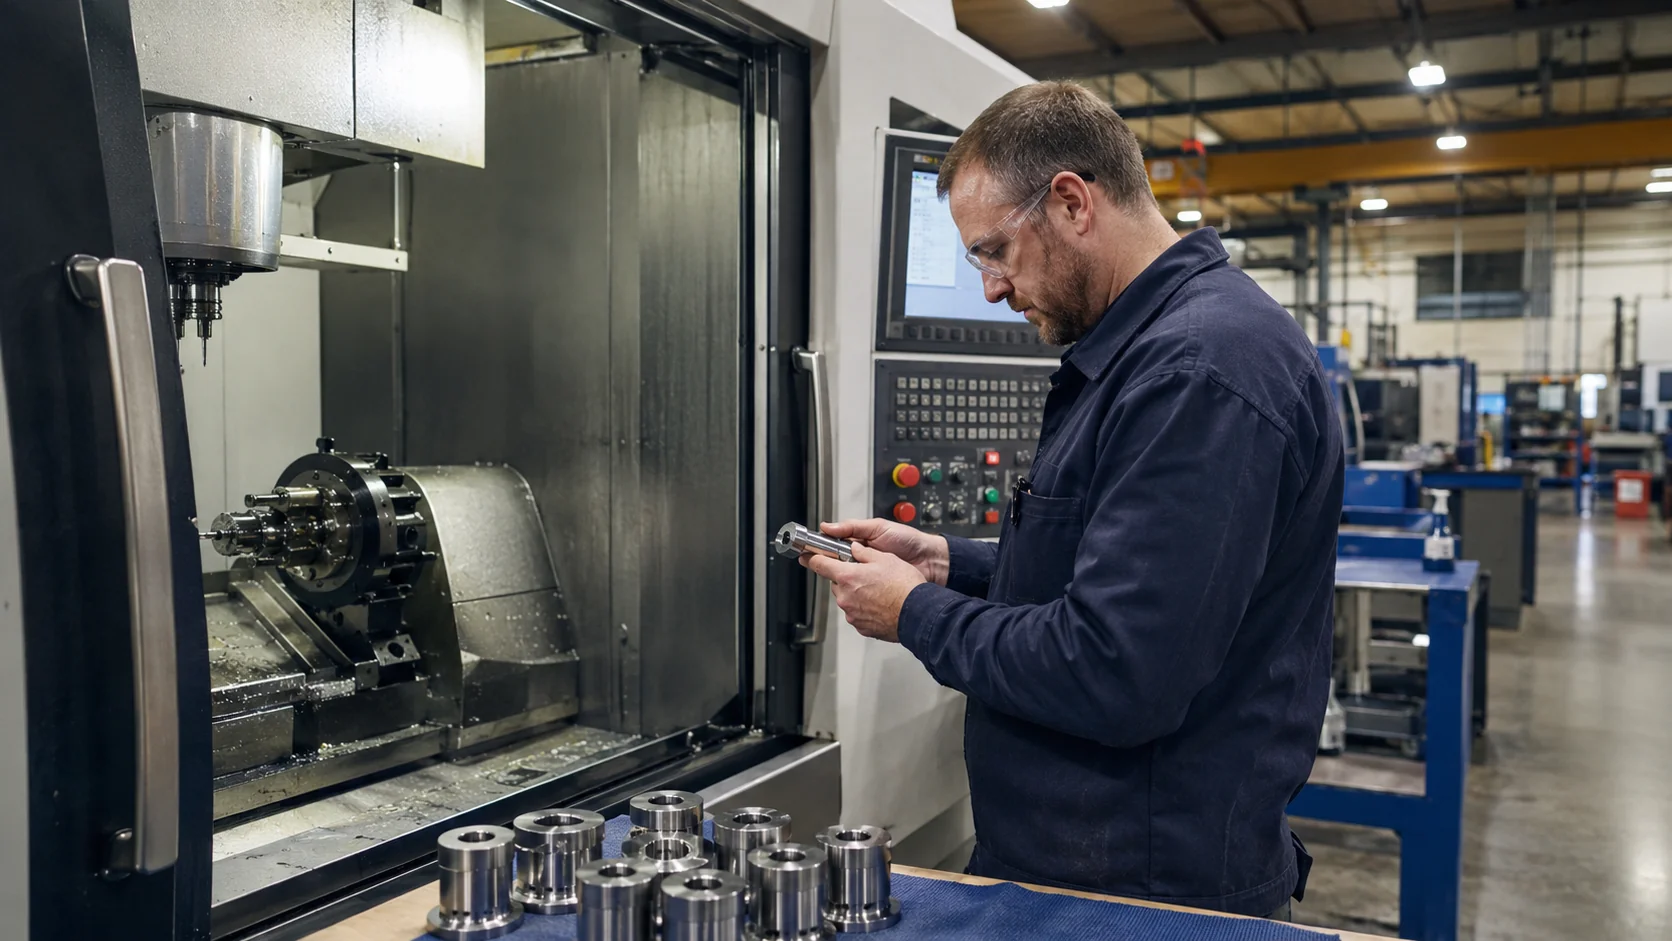
For Windsor–Essex fabrication shops, machining and metalworking plants, plastics and assembly operations, and job-shop or tool-and-die producers — reviewed through an independent broker who can coordinate property, products liability, business interruption, equipment breakdown, and specialty coverages for how you actually manufacture.
What's covered
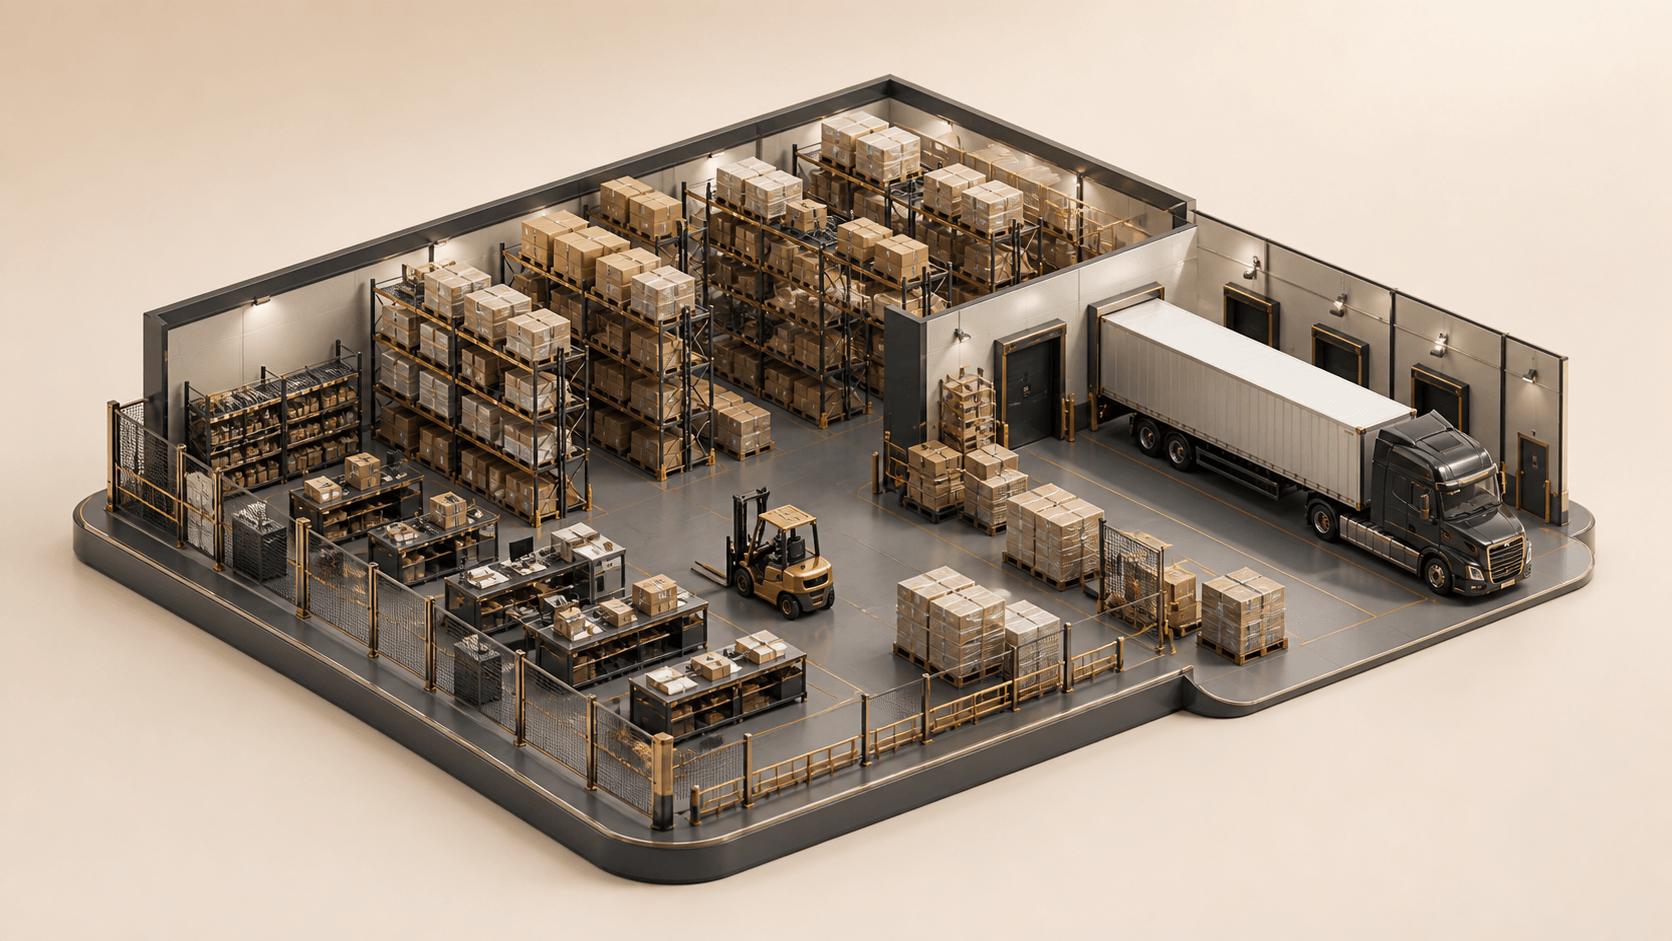
Manufacturing insurance is organized here around five exposures most Windsor–Essex plants and job shops review first — product liability, property and stock, income after a covered physical loss, equipment breakdown where purchased, and job-shop-specific values — because each insuring agreement has different triggers, limits, and endorsements.
A defective part can follow your product long after it leaves the dock: Manufacturers and assemblers face products-completed operations exposure when a customer or downstream user alleges injury or damage from a part, component, or finished good you produced — including precision work to customer specifications on many programs. Commercial general liability may address certain covered claims subject to policy wording, but it does not automatically pay product recall or withdrawal expenses, warranty rework, or every contractual quality dispute. Product recall insurance is a separate first-party discussion on our product recall page.
A defective part can follow your product long after it leaves the dock
Manufacturers and assemblers face products-completed operations exposure when a customer or downstream user alleges injury or damage from a part, component, or finished good you produced — including precision work to customer specifications on many programs. Commercial general liability may address certain covered claims subject to policy wording, but it does not automatically pay product recall or withdrawal expenses, warranty rework, or every contractual quality dispute. Product recall insurance is a separate first-party discussion on our product recall page.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Manufacturing insurance FAQ
Straight answers to common questions for this industry.
Most Windsor–Essex manufacturers start with commercial general liability — including products-completed operations — and commercial property for buildings, machinery, and stock. Business interruption, equipment breakdown, commercial auto, pollution, product recall, crime, and cyber are added when operations, contracts, or exposures warrant them — each subject to separate policy terms. There is no single universal manufacturing policy that automatically bundles every coverage type.
Ready when you are
Ready to review your manufacturing program?
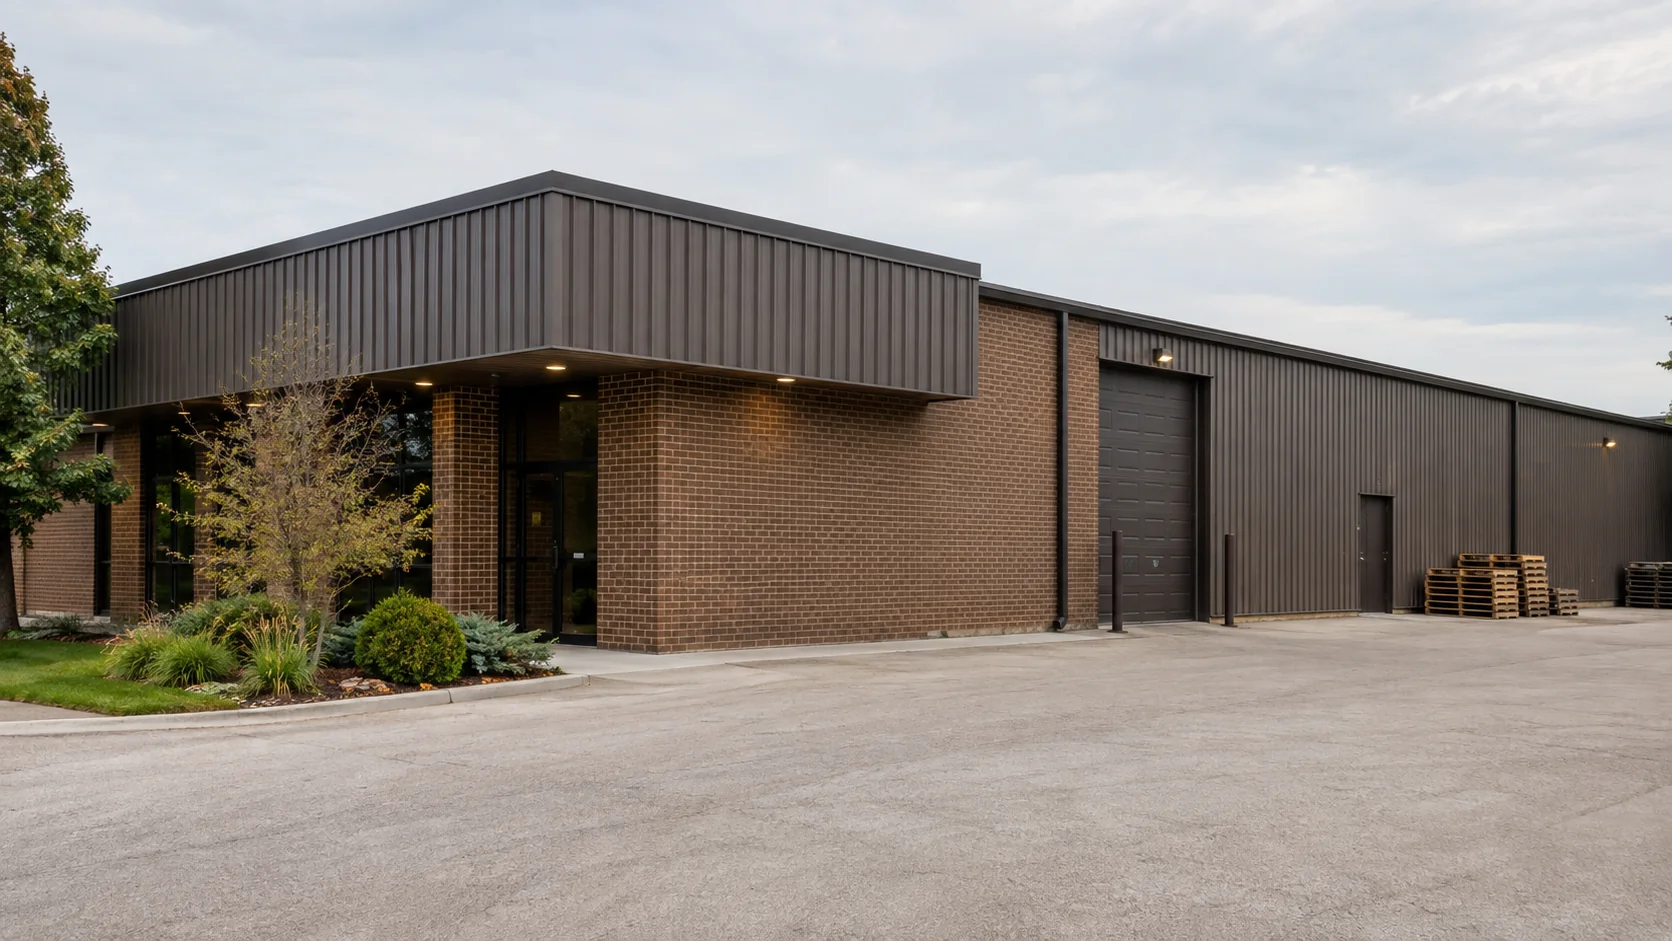
Share your facility, products, equipment values, and production flow — we will compare commercial markets and explain what fits.