
Commercial Insurance · Windsor-Essex
Salon & Barber Insurance
Hair salons and barbershops combine two different exposure types: premises liability for customers in your reception and service areas, and professional treatment liability for cuts, colour, chemical services, and other hands-on work. Depending on what you offer, that can mean general liability for slip-and-fall incidents, treatment or professional liability for service-related injury or reaction claims, property coverage for stations and equipment, and product liability where you retail hair or skin products — each subject to the policies you purchase. Not every salon provides nails, waxing, laser, medical aesthetics, or mobile services, and higher-risk treatments must be disclosed rather than assumed to be included. Premium Insurance Brokers can help align coverage to your actual service menu and staffing model.
For Windsor–Essex hair salons, barbershops, and personal-care operators — reviewed through an independent broker who can coordinate premises, treatment, property, and product coverage for the services you actually provide.
What's covered
Salon and barber insurance usually combines premises liability with professional treatment exposure for the services you perform — plus property and product coverage where relevant — depending on your menu, retail sales, and whether stylists are employees or independent renters.
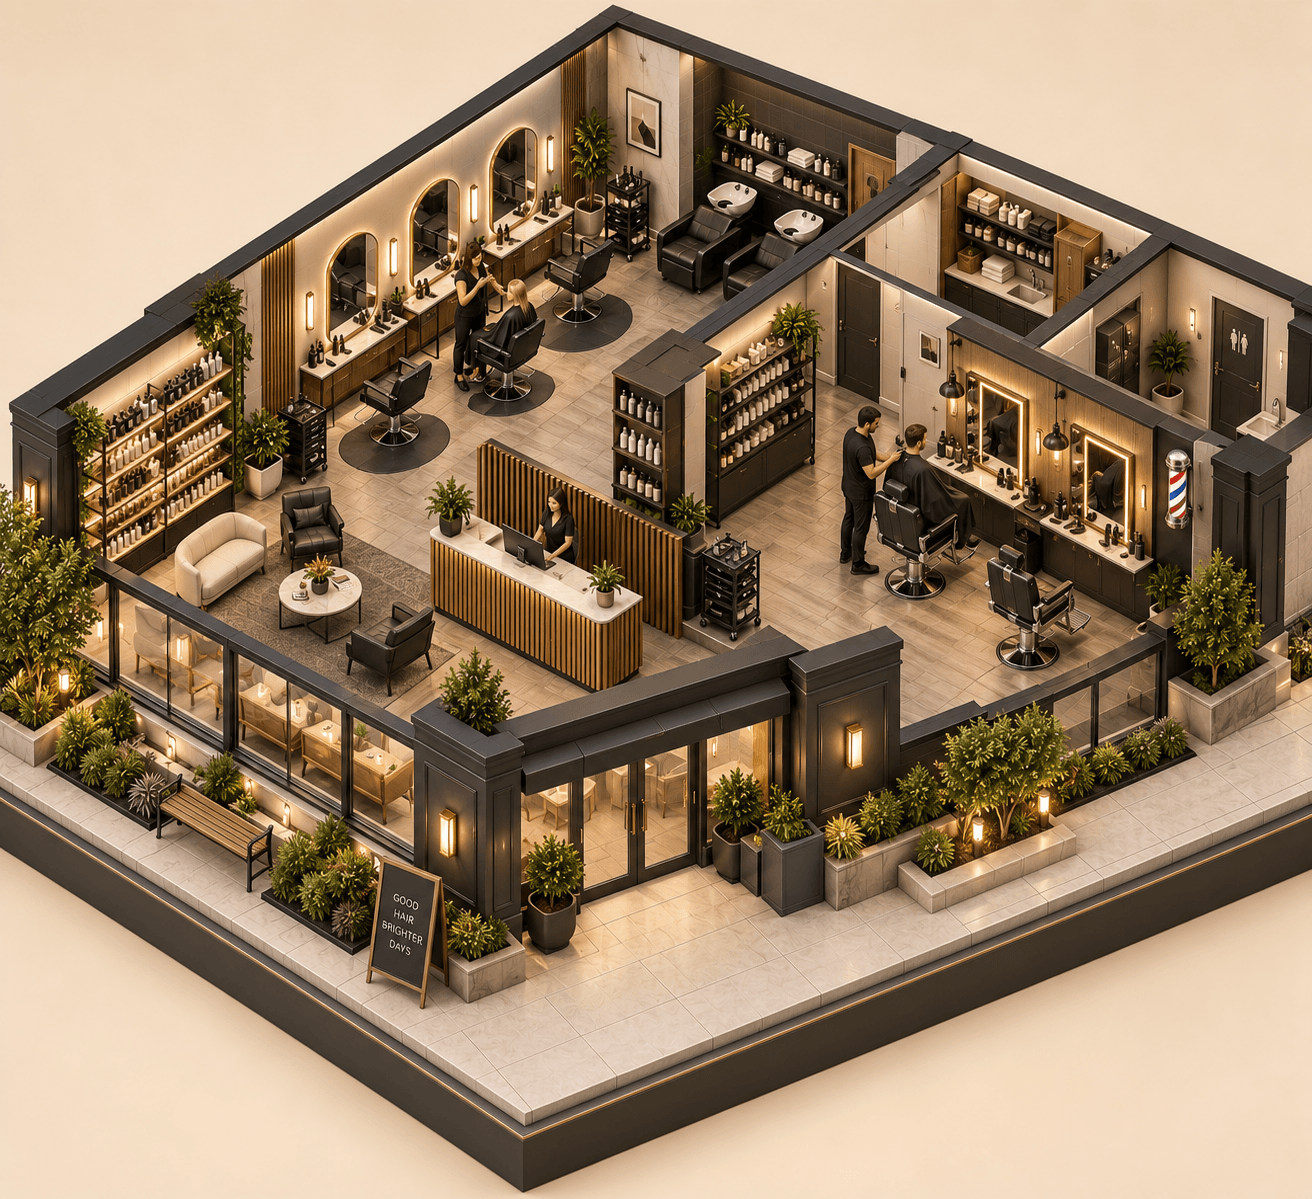
When a wet floor in reception becomes a premises claim: Salons and barbershops concentrate clients in reception areas, walkways, and wash stations where wet floors, cords, and product spills create slip-and-fall exposure distinct from a treatment-gone-wrong claim. General liability may address certain premises and operations claims, but scope depends on policy wording and how your location, chair-rental model, and any mobile services are disclosed during underwriting.
When a wet floor in reception becomes a premises claim
Salons and barbershops concentrate clients in reception areas, walkways, and wash stations where wet floors, cords, and product spills create slip-and-fall exposure distinct from a treatment-gone-wrong claim. General liability may address certain premises and operations claims, but scope depends on policy wording and how your location, chair-rental model, and any mobile services are disclosed during underwriting.
Practical considerations
The Premium difference
Why a broker?
One relationship. Multiple markets. Coverage explained in plain language.
- 1
Your operation
Your industry, locations, and how the business actually runs day to day.
- 2
Multiple insurance markets
Independent access to commercial carriers — options compared side by side.
- 3
Premium broker
Windsor-Essex guidance that translates policy wording into decisions.
- 4
Right-fit coverage
Protection aligned to your operations — not generic off-the-shelf limits.
A lot to protect? Good thing we have options.
One policy is rarely the whole picture. Explore other commercial coverage from Premium.
Salon & barber FAQ
Straight answers to common questions.
Treatment or professional liability may help respond to certain claims alleging injury, burns, or allergic reaction from services you performed — subject to policy terms, disclosed services, and exclusions. A premises slip-and-fall is a different claim type from a colour reaction. Confirm which coverage applies and whether your service menu is fully disclosed to your broker.
Ready when you are
Run a salon or barber shop?
Share your services, staff structure, and product sales — we will compare personal care coverage.